
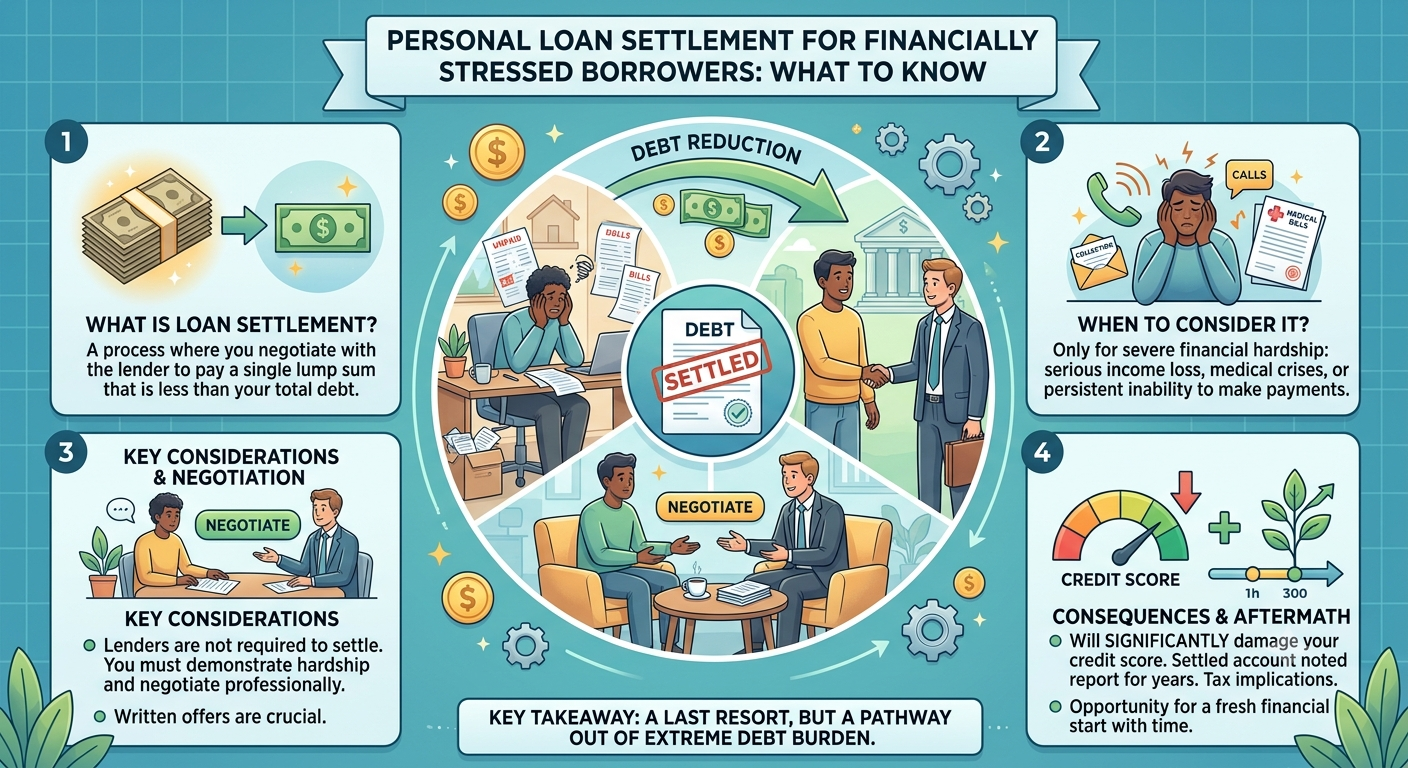
Unforeseen life challenges—such as job losses, medical crises, or business downturns—can suddenly make monthly loan payments impossible to manage. When debt balances grow rapidly due to compounding interest and overdue fees, financially stressed borrowers often feel overwhelmed. In these situations, continuing full Equated Monthly Installment (EMI) repayments may no longer be realistic.
For individuals facing severe financial hardship, pursuing a formal compromise resolution offers a legal way to reduce liabilities and resolve debt obligations safely. Understanding how personal debt compromises work enables you to protect your legal rights and establish a clear path toward financial stability.
What Is a Personal Loan Settlement?
A personal compromise resolution is an official agreement between a borrower and a lending institution. Under this arrangement, the bank or Non-Banking Financial Company (NBFC) agrees to accept a mutually negotiated, discounted lump-sum payment to fully discharge the debt, forgiving the remaining balance.
Key aspects of this process include:
- Waiver of Penal Fees: Negotiated resolutions typically waive accumulated late payment penalties, penal interest rates, and processing surcharges.
- Principal Discount: Depending on the severity of financial hardship, lenders may forgive a portion of the original principal balance to close delinquent accounts.
- Cessation of Recovery Actions: Once formal settlement negotiations begin, aggressive collection calls and recovery agent visits must cease under regulatory guidelines.
Regular Loan Restructuring vs. Compromise Settlement
| Feature | Standard Loan Restructuring | Compromise Loan Settlement |
| Primary Objective | Extend tenure to reduce EMI amounts | Eliminate total debt via a discounted lump sum |
| Financial Qualification | Requires stable, ongoing income | Applies to cases of verified, severe financial distress |
| Credit Report Impact | Minimal effect; reported as restructured | Account marked as “Settled” on credit bureau files |
| Total Payable Amount | Increases long-term interest costs | Reduces total debt balance significantly |
Essential Steps for Distressed Borrowers
To successfully resolve delinquent obligations without exposing yourself to legal or financial complications, follow these essential steps:
- Gather Proof of Financial Hardship: Maintain clear documentation of your financial situation, such as medical records, lay-off letters, or business loss statements, to prove genuine inability to pay.
- Avoid Paying Informal Collectors: Never transfer funds directly to collection representatives. All payments must be made strictly to the financial institution’s official account.
- Insist on Written Authorization: Pay only after receiving an official Settlement Sanction Letter printed on the lender’s letterhead, specifying the agreed compromise amount and terms.
- Secure Official Discharge Documents: After making the final payment, obtain a formal No Dues Certificate (NDC) to confirm full account closure.
Protecting Your Rights with Professional Advisory
Navigating negotiations with institutional credit committees while dealing with financial distress can be intimidating. Working alongside experienced financial advisers ensures your hardship is presented effectively and negotiated under governing regulatory frameworks.
Partnering with an established loan settlement agency provides immediate defense against unlawful recovery practices. A reputable loan settlement agency handles all formal correspondence with lenders, shielding you from workplace harassment and coercive tactics.
Utilizing specialized loan settlement services ensures your financial hardship case is audited and represented thoroughly. Comprehensive loan settlement services assist in reviewing outstanding balances, disputing incorrect penal charges, and establishing realistic settlement terms.
Consulting an accredited loan settlement expert gives you crucial leverage during formal compromise discussions. A dedicated loan settlement expert evaluates your repayment capacity, safeguards your rights under Reserve Bank of India (RBI) guidelines, and negotiates optimal One-Time Settlement (OTS) terms.
Executing a structured loan settlement provides immediate relief from overwhelming debt obligations. Once a negotiated loan settlement sum is remitted directly to the lender, you receive formal written clearance, permanently ending legal and recovery actions.
If mounting debts are causing severe stress, pursuing a tailored loan settlement provides a clear route back to financial peace. Working with a trusted loan settlement expert ensures your legal rights are protected, while relying on proven loan settlement services helps prepare your profile for long-term recovery.
Experiencing severe financial hardship does not mean you have to remain trapped in endless debt. By understanding your rights, securing written documentation, and working with accredited resolution professionals, you can eliminate unmanageable liabilities safely and start rebuilding your financial independence.