
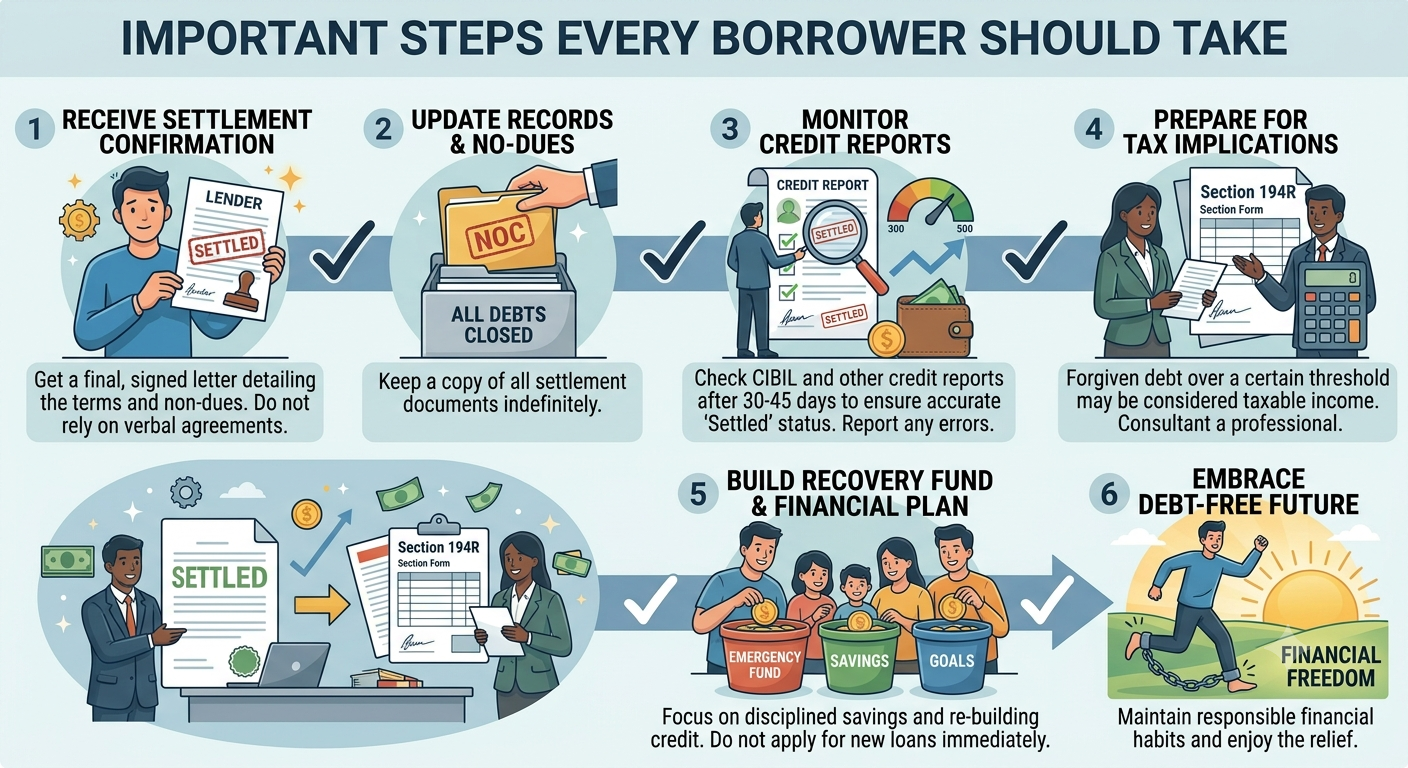
Completing a One-Time Settlement (OTS) with your lending institution brings immediate emotional and financial relief. Resolving delinquent debt allows borrowers to stop recovery harassment, halt compounding interest fees, and focus on rebuilding their financial health. However, paying the agreed settlement sum is only the first part of achieving true financial recovery.
To ensure the settlement is legally binding, your credit records reflect accurate account status, and future creditworthiness is protected, borrowers must complete critical post-settlement steps.
Step 1: Secure the Official No Dues Certificate (NDC)
Remitting the negotiated settlement payment does not automatically update your institutional file. You must secure formal documentation confirming full legal closure.
- Request a Written NDC / Closure Letter: Obtain a physical document printed on official bank stationery and signed by an authorized signatory.
- Verify Key Information: Ensure the certificate explicitly references your loan account number, states that the agreed sum was received, and confirms all financial claims against you are permanently discharged.
- Retain Permanent Copies: Store physical and digital copies securely; this document is your ultimate protection against future collection disputes.
Step 2: Retrieve Security Instruments and Collateral Documents
If your defaulted debt involved security deposits, post-dated cheques, or collateral, ensure all assets and instruments are returned promptly:
- Retrieve Cancelled Post-Dated Cheques (PDCs): Request the return or verified destruction of all unused cheques held by the lender.
- Revoke Electronic Clearing (NACH/ECS) Mandates: Ensure the bank cancels automated debit instructions so no future payment requests occur.
- Reclaim Property Documents (For Secured Debt): Collect original title deeds, vehicle registration documents, or pledges once encumbrances are removed.
Post-Settlement Action Items & Verification Checklist
| Essential Action Item | Verification Objective | Recommended Completion Window |
| No Dues Certificate (NDC) | Confirm full legal discharge of debt liability | Within 7 to 10 days post-payment |
| Security Instrument Retrieval | Recover uncashed PDCs and cancel NACH mandates | Within 15 days post-payment |
| CIBIL / Bureau Audit | Verify account status reflects “Settled” accurately | 30 to 45 days post-payment |
| Legal Notice Closure | Ensure ongoing court or arbitration cases are withdrawn | Within 30 days post-payment |
Step 3: Monitor Credit Bureau Reports (CIBIL Audit)
Lenders report settled accounts to credit registries (such as CIBIL, Experian, or Equifax) during standard reporting cycles:
- Verify Bureau Status: Confirm that your account balance is marked as zero and designated as “Settled” rather than active default.
- Dispute Bureau Inaccuracies: If the lender fails to update your record within 45 days, file a formal dispute with credit bureaus alongside your official NDC.
Step 4: Rebuild Credit Score and Re-Establish Financial Health
While a “Settled” status temporarily lowers your credit rating, consistent financial discipline will restore your creditworthiness over time:
- Open a Secured Credit Card: Apply for a credit card backed by a Fixed Deposit (FD) to build a positive payment track record.
- Maintain Zero Default History: Pay utility bills, mobile subscriptions, and new obligations on time.
- Keep Credit Utilization Low: Utilize less than 30% of available credit limits to demonstrate responsible borrowing behavior.
Securing Legal Protection and Credit Recovery Support
Managing post-settlement administrative verification while repairing credit scores requires careful attention to legal detail. Working with professional advisors ensures your settlement rights are fully enforced across institutional channels.
Engaging an established loan settlement agency guarantees your account receives proper legal closure. A dedicated loan settlement agency handles post-settlement disputes, ensures security instruments are retrieved, and stops unexpected recovery claims.
Utilizing dedicated loan settlement services provides complete administrative tracking after payment. Comprehensive loan settlement services audit bank submission files to confirm that your debt waiver terms are respected.
Consulting a recognized loan settlement expert streamlines your credit recovery roadmap. An experienced loan settlement expert reviews your CIBIL report, files bureau dispute rectifications, and guides your financial reconstruction.
Executing a strategic loan settlement marks the start of a clean financial slate. Once you complete the loan settlement process and secure your No Dues Certificate, you eliminate legal risk and set the stage for long-term stability.
If you have completed a debt compromise, pursuing a structured loan settlement action plan ensures lasting peace of mind. Collaborating with a qualified loan settlement expert and leveraging reliable loan settlement services protects your legal rights and helps rebuild your financial future.
Achieving true financial recovery after a loan settlement requires diligence, proper documentation, and ongoing credit repair. By securing your No Dues Certificate, retrieving security instruments, and working with expert guidance, you can permanently close your past liabilities and rebuild your financial independence.