
For many individuals, purchasing a home is a major life goal. However, if you have previously gone through a One-Time Settlement (OTS) to manage unmanageable debt, you might wonder how that choice impacts your future mortgage eligibility.
Can a loan settlement affect your ability to buy a home in the future? Yes, it can—but it is not a permanent barrier. While a loan settlement temporarily impacts your credit bureau report, taking proactive steps allows you to rebuild your credit standing and successfully qualify for a home loan over time.
How a Loan Settlement Impact Works on Credit Reports
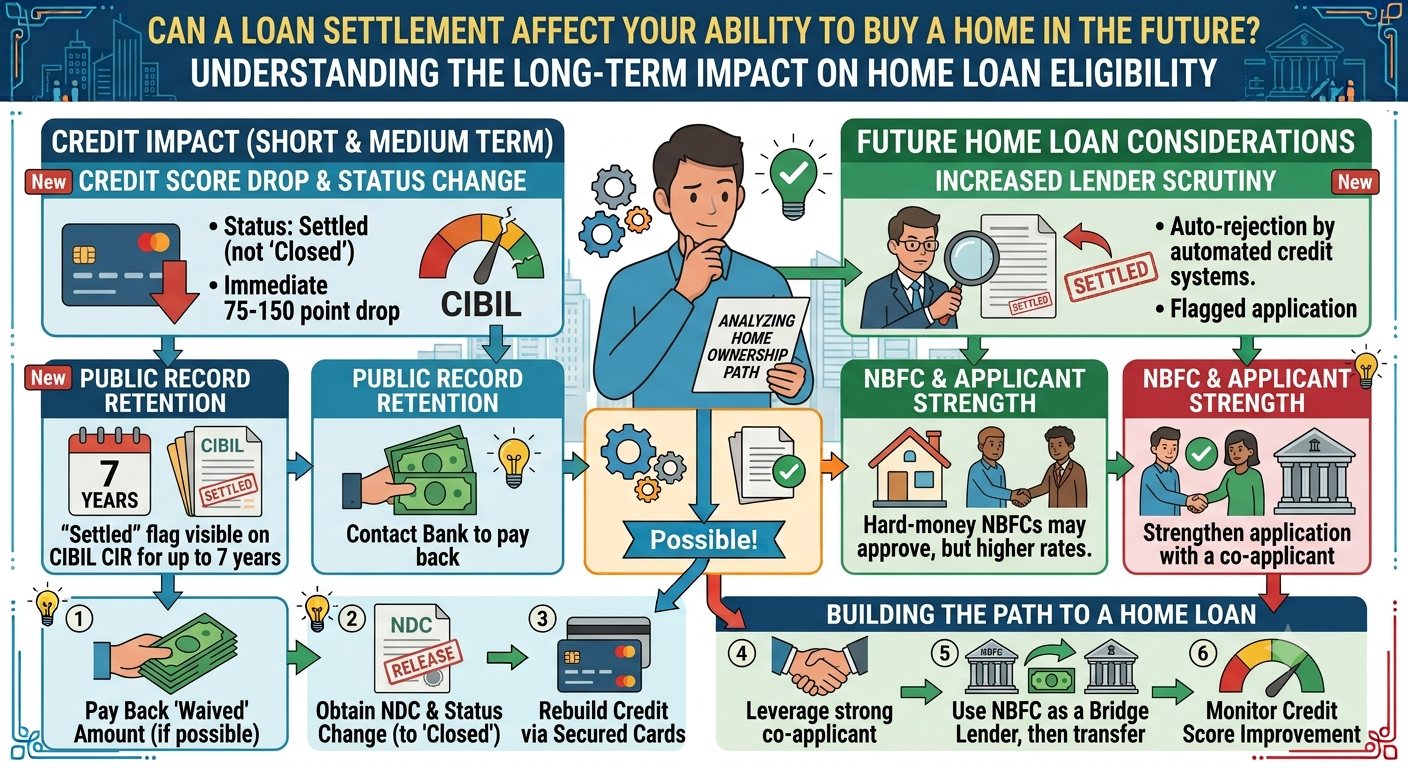
When you complete a loan settlement, the lender agrees to accept a reduced sum to discharge the debt. Because the lender forgives a portion of the original balance, the account is reported to bureaus like CIBIL or Experian with a status of “Settled” rather than “Closed.”
Here is how this status affects your home loan application:
- Immediate Credit Score Drop: A “Settled” status leads to a short-term drop in your credit score, typically placing it below preferred mortgage lending thresholds (usually 750+).
- Underwriting Red Flags: Automated underwriting systems and bank loan officers view a “Settled” remark as a sign of past default, making them cautious about granting large long-term loans.
- Higher Interest Rates or Lower LTV: In the initial years post-settlement, non-banking financial companies (NBFCs) or specialized housing finance institutions may offer home loans, but they may charge higher interest rates or require a lower Loan-to-Value (LTV) ratio.
Key Milestones: Recovering Your Mortgage Eligibility
| Recovery Phase | Timeline | Primary Credit Activity | Mortgage Impact |
| Immediate Post-Settlement | Months 1–12 | Obtain No Dues Certificate (NDC) & verify bureau updates | High difficulty for traditional bank mortgages |
| Active Profile Rebuilding | Years 1–2 | Maintain secured credit cards & pay utility bills on time | Eligible for specialized NBFC housing finance |
| Credit Restoration | Years 3–4 | Reach CIBIL score of 720–750+ through clean repayment history | Prime consideration from mainstream housing lenders |
| Full Recovery & Closure | Years 5+ | Past settlement remarks carry minimal weight | Unrestricted eligibility for competitive home loan rates |
Actionable Steps to Qualify for a Home Loan After Settlement
If you plan to buy a home after settling past debts, following a clear recovery strategy will help rebuild your creditworthiness:
- Obtain Legal Proof of Closure: Ensure you receive a formal Settlement Sanction Letter and a No Dues Certificate (NDC) from the bank once the payment is made.
- Audit Credit Bureau Reports: Confirm that credit bureaus update the loan status accurately and that the outstanding balance reflects zero.
- Build Positive Credit History: Use secured credit cards (backed by fixed deposits) or small consumer durable loans, ensuring 100% on-time payments to rebuild your score.
- Accumulate a Higher Down Payment: Presenting a larger down payment (20% to 30%) reduces the lender’s risk and improves mortgage approval chances.
Rebuilding Credit Stability with Professional Guidance
Managing the path from debt settlement to homeownership requires careful financial planning. Working with financial professionals ensures your past debt resolutions are handled correctly and do not hinder your long-term goals.
Partnering with an established loan settlement agency helps ensure your settlement process is legally sound. A dedicated loan settlement agency manages lender communications and ensures all post-settlement documentation is issued properly.
Utilizing specialized loan settlement services provides structural guidance for long-term recovery. Comprehensive loan settlement services assist in reviewing credit bureau reports, disputing reporting errors, and establishing a clear path toward financial stability.
Consulting an accredited loan settlement expert allows you to navigate debt negotiations without compromising future borrowing needs. A skilled loan settlement expert negotiates favorable settlement terms that minimize negative credit remarks where possible.
Executing a structured loan settlement gives you immediate relief from unmanageable debt, allowing you to refocus on long-term wealth building. Once an agreed loan settlement is completed, you can systematically work toward regaining home loan eligibility.
If past debt obligations are holding you back, seeking a tailored loan settlement strategy provides a clean start. Working alongside a dedicated loan settlement expert protects your rights, while trusted loan settlement services help prepare your profile for future homeownership.
A past loan settlement does not mean you cannot buy a home in the future. By securing official closure documents, actively rebuilding your credit score, and seeking professional guidance, you can clear old liabilities and successfully secure a home loan.