
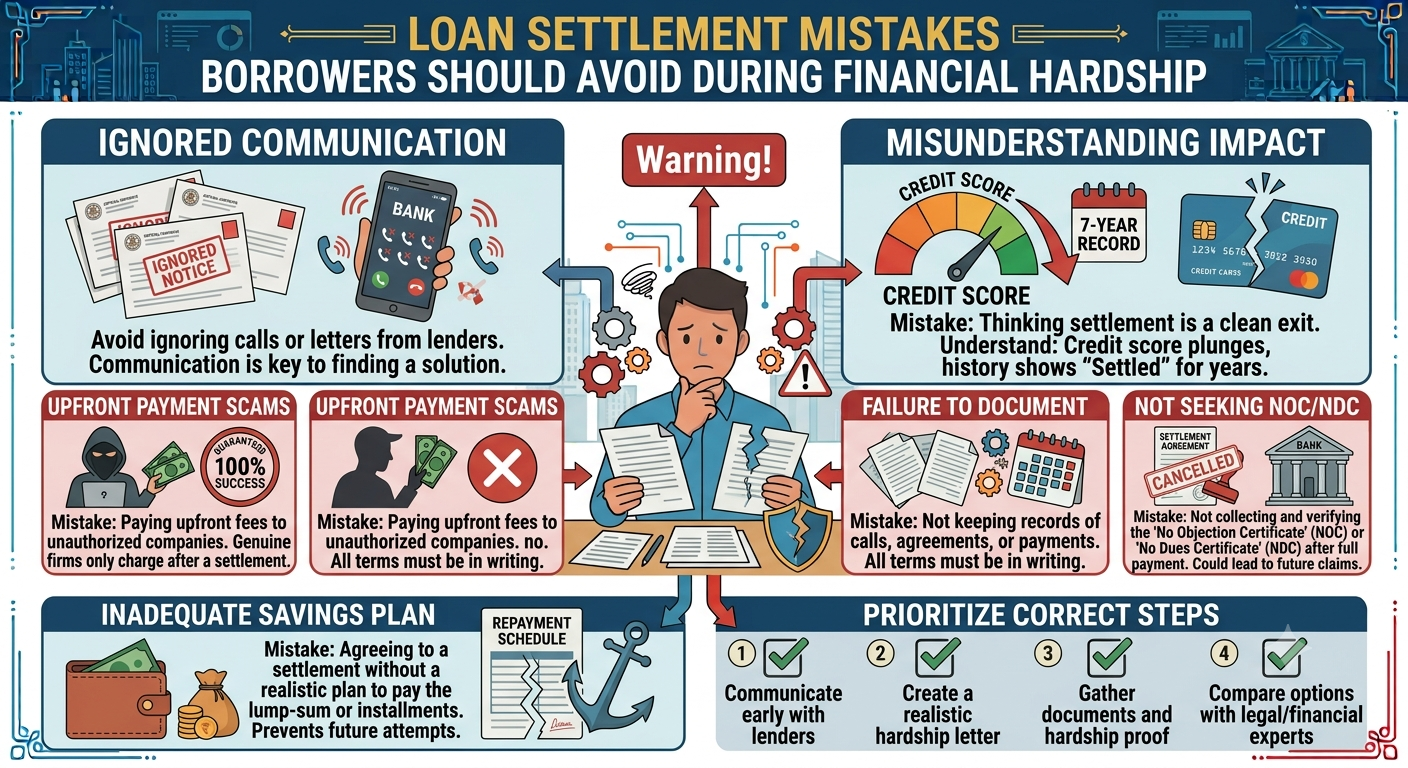
Experiencing severe financial distress—whether due to job loss, medical emergencies, or economic downturns—can leave even the most responsible borrowers struggling to meet their debt obligations. When monthly Equated Monthly Installments (EMIs) become unmanageable, negotiating a compromise settlement often provides a critical escape route from spiraling liabilities.
However, navigating debt resolution without proper guidance is fraught with pitfalls. A single misstep can lead to legal complications, unexpected tax liabilities, or prolonged credit damage. Understanding the most common errors borrowers commit allows you to protect your legal rights and achieve a clean slate.
Critical Errors to Avoid During Debt Resolution
When facing heavy debts, panic can cause borrowers to make rushed decisions. Avoid these major blunders during negotiations:
- Relying on Verbal Promises: Never make any compromise payment based on phone calls or informal promises from collection representatives. Always insist on an official, written Settlement Sanction Letter generated directly by the bank or financial institution.
- Transferring Funds to Private Accounts: Recovery agents may request partial payments into personal accounts or third-party agencies under the guise of “processing fees.” All settlement funds must be remitted directly to the lender’s registered loan account.
- Ignoring Legal and Demand Notices: Disregarding communications from financial institutions can prompt formal legal actions, including proceedings under civil recovery laws or arbitration. Prompt, formal responses are essential.
- Failing to Secure Post-Settlement Documents: Making the agreed settlement payment without receiving a No Dues Certificate (NDC) or formal discharge document leaves the account open to future disputes.
Common Settlement Pitfalls vs. Correct Recovery Actions
| Critical Error | Immediate Financial Risk | Recommended Best Practice |
| Paying Without Written Approval | Loss of money without debt discharge | Pay only after verifying an official Settlement Sanction Letter |
| Rushing Unaffordable Terms | Defaulting on the settlement agreement | Negotiate realistic, manageable One-Time Settlement (OTS) terms |
| Ignoring Bureau Discrepancies | Uncorrected reporting errors on credit bureau files | Audit credit reports post-settlement and dispute inaccuracies |
| Negotiating Under Panic | Accepting unfavourable compromise conditions | Seek accredited advisory and professional representation |
Step-by-Step Strategy to Safeguard Your Resolution
To ensure your debt resolution process yields binding legal relief without unexpected complications, execute these strategic steps:
- Audit Total Outstanding Liabilities: Distinguish between principal dues, interest charges, and penal fees before initiating discussions.
- Maintain Written Documentation: Keep comprehensive records of all letters, emails, and compromise proposals exchanged with lending officials.
- Verify Official Sanction Letters: Examine the sanction letter for exact waiver amounts, payment deadlines, and account numbers before making payment.
- Obtain Legal Closure Proof: Secure a formal No Dues Certificate and verify that credit bureau records accurately reflect the account status as zero balance.
Navigating Debt Recovery Safely with Professional Guidance
Resolving unmanageable debt requires strategic representation, thorough documentation, and a clear understanding of banking regulations. Partnering with seasoned advisers ensures that your financial recovery remains legally protected at every stage.
Engaging a reliable loan settlement agency provides structural protection against aggressive collection tactics. A dedicated loan settlement agency handles formal correspondence with financial institutions, shielding you from workplace harassment and unlawful recovery efforts.
Utilizing specialized loan settlement services guarantees that your hardship case is properly structured and presented. Comprehensive loan settlement services assist in reviewing outstanding balances, challenging unfair penal charges, and establishing realistic settlement timelines under Reserve Bank of India (RBI) guidelines.
Consulting an experienced loan settlement expert gives you critical leverage when negotiating with credit committees. A skilled loan settlement expert evaluates your repayment capacity and secures maximum permissible waivers on interest and default penalties.
Executing a verified loan settlement brings permanent legal relief from overwhelming liabilities. Once an agreed loan settlement sum is remitted directly to the lender, you receive formal written clearance, ending recovery actions completely.
If unmanageable obligations are causing severe strain, seeking a structured loan settlement offers a secure pathway back to stability. Working alongside a trusted loan settlement expert ensures your legal rights are protected, while relying on top-tier loan settlement services helps prepare your financial profile for long-term recovery.
Avoiding critical errors during debt resolution is vital to achieving genuine financial freedom. By insisting on written documentation, paying lenders directly, and seeking expert representation, you can clear unmanageable debts safely and begin rebuilding your financial future.