
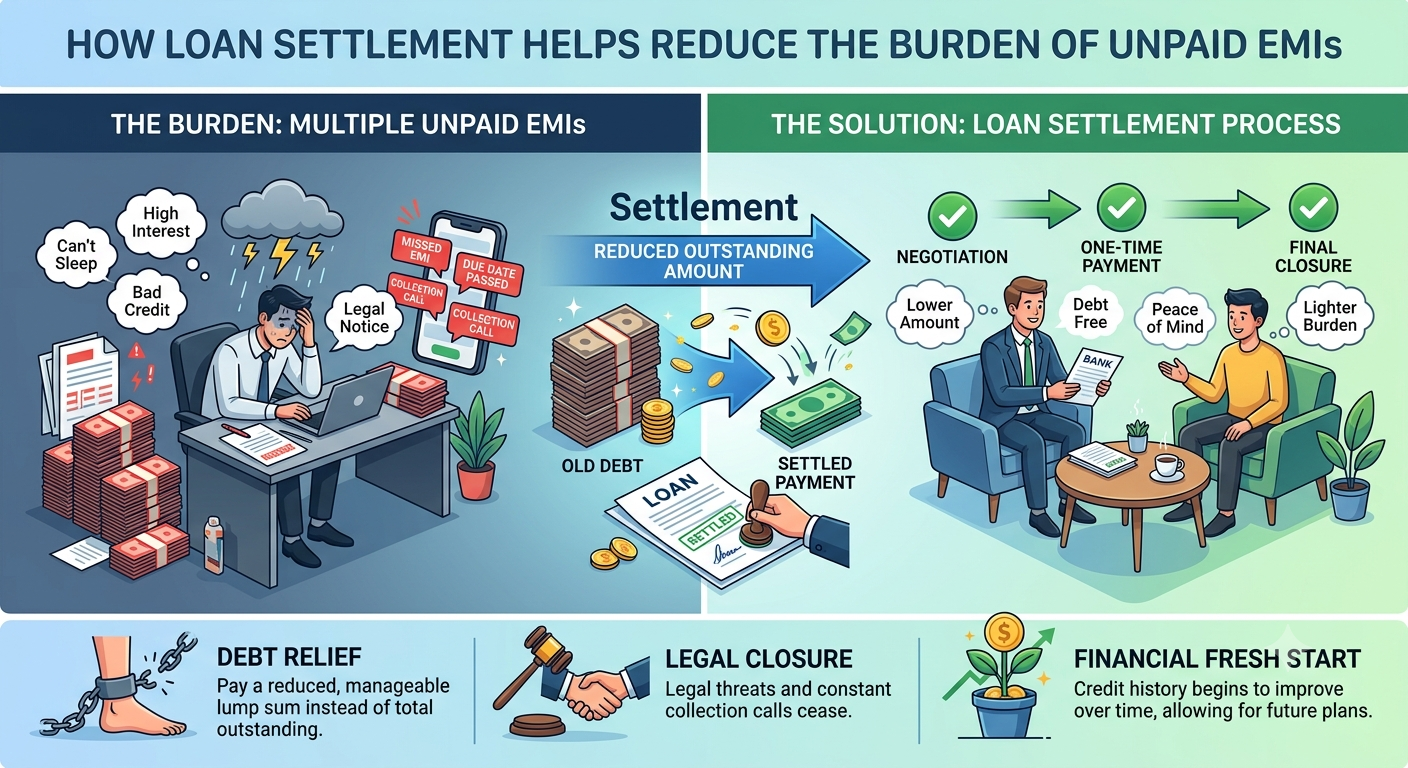
Financial hardship can strike unexpectedly. Job loss, medical emergencies, or sudden business downturns can leave even the most disciplined individuals struggling to make their monthly Equated Monthly Installments (EMIs). When unpaid EMIs begin to stack up, compounding interest, late payment charges, and aggressive recovery calls create immense psychological and financial pressure.
For borrowers trapped in a debt spiral where regular repayment is mathematically impossible, continuing to default only worsens the situation. In such scenarios, negotiating a formal compromise resolution provides a legally sanctioned exit strategy, helping you eliminate spiraling liabilities and regain peace of mind.
Understanding the Burden of Unpaid EMIs
Defaulting on an EMI starts a chain reaction that quickly multiplies your total debt burden. Understanding how lenders handle unpaid installments highlights why early intervention is necessary:
- Compounding Penal Interest: Banks add penal charges (often 2% to 3% per month) on top of regular interest for every missed installment, inflating the total balance rapidly.
- Aggressive Collection Efforts: As defaults stretch past 60 to 90 days, accounts transition into Non-Performing Assets (NPAs), leading to intense collection calls and legal notices.
- Severe Credit Score Degradation: Overdue payments are reported to credit bureaus monthly, drastically lowering your credit score and damaging future borrowing capacity.
Unpaid EMI Escalation vs. Settlement Relief
| Financial Metric | Continuing Unpaid EMI Defaults | Executing Compromise Settlement |
| Total Debt Amount | Increases continuously due to compound fees | Reduced significantly (often 40% to 60% waiver) |
| Legal Exposure | High risk of arbitration, civil suits, or legal notices | Complete closure of legal cases upon final payment |
| Collection Pressure | Persistent calls and field recovery visits | Immediate cessation of recovery actions |
| Account Status | Marked as severe default / NPA | Closed as “Settled” with zero balance owed |
How Compromise Resolutions Provide Financial Relief
A One-Time Settlement (OTS) is an official mechanism where a bank or non-banking financial company (NBFC) agrees to accept a discounted lump-sum payment to forgive the remaining balance and close the loan account. Here is how it alleviates financial stress:
- Waiver of Penal Charges and Interest: Negotiated settlements typically eliminate accumulated default fees, late charges, and accrued interest, leaving only a reduced portion of the principal.
- Cessation of Recovery Harassment: Once a formal settlement agreement is reached and sanctioned, recovery representatives are legally required to stop contacting you or visiting your workplace.
- Affordable Lump-Sum or Phased Payments: Lenders often allow the reduced settlement figure to be paid in a single lump sum or structured across short installments based on proven hardship.
- Complete Legal Discharge: Paying the agreed amount yields a Settlement Sanction Letter followed by a No Dues Certificate (NDC), ensuring the lender cannot claim remaining balances in the future.
Reclaiming Financial Freedom with Professional Assistance
Attempting to negotiate directly with institutional credit committees while under stress often leads to unfair terms or unfulfilled promises. Securing expert guidance ensures your hardship is presented effectively and negotiated under governing regulatory frameworks.
Partnering with an established loan settlement agency provides vital structural protection against unlawful collection practices. A specialized loan settlement agency manages all official correspondence with lenders, preventing harassment at home and work.
Utilizing dedicated loan settlement services ensures your financial hardship case is properly audited and submitted. Comprehensive loan settlement services help review outstanding dues, challenge unjustified penal fees, and secure optimal discount terms.
Consulting an accredited loan settlement expert gives you strong leverage during formal negotiations. A skilled loan settlement expert evaluates your repayment capacity, shields your rights under Reserve Bank of India (RBI) guidelines, and negotiates realistic One-Time Settlement (OTS) options.
Executing a structured loan settlement brings permanent relief from unmanageable unpaid EMIs. Once an agreed loan settlement sum is remitted directly to the financial institution, you receive full written closure.
If mounting EMI defaults are disrupting your life, pursuing a tailored loan settlement offers a clear path toward financial recovery. Working alongside a trusted loan settlement expert ensures your interests are safeguarded, while relying on proven loan settlement services helps prepare your profile for long-term financial stability.
Unpaid EMIs do not have to result in lifelong financial ruin. By securing formal legal closure, negotiating reasonable compromise terms, and working with experienced advisers, you can break free from unmanageable debt and rebuild your financial future.