
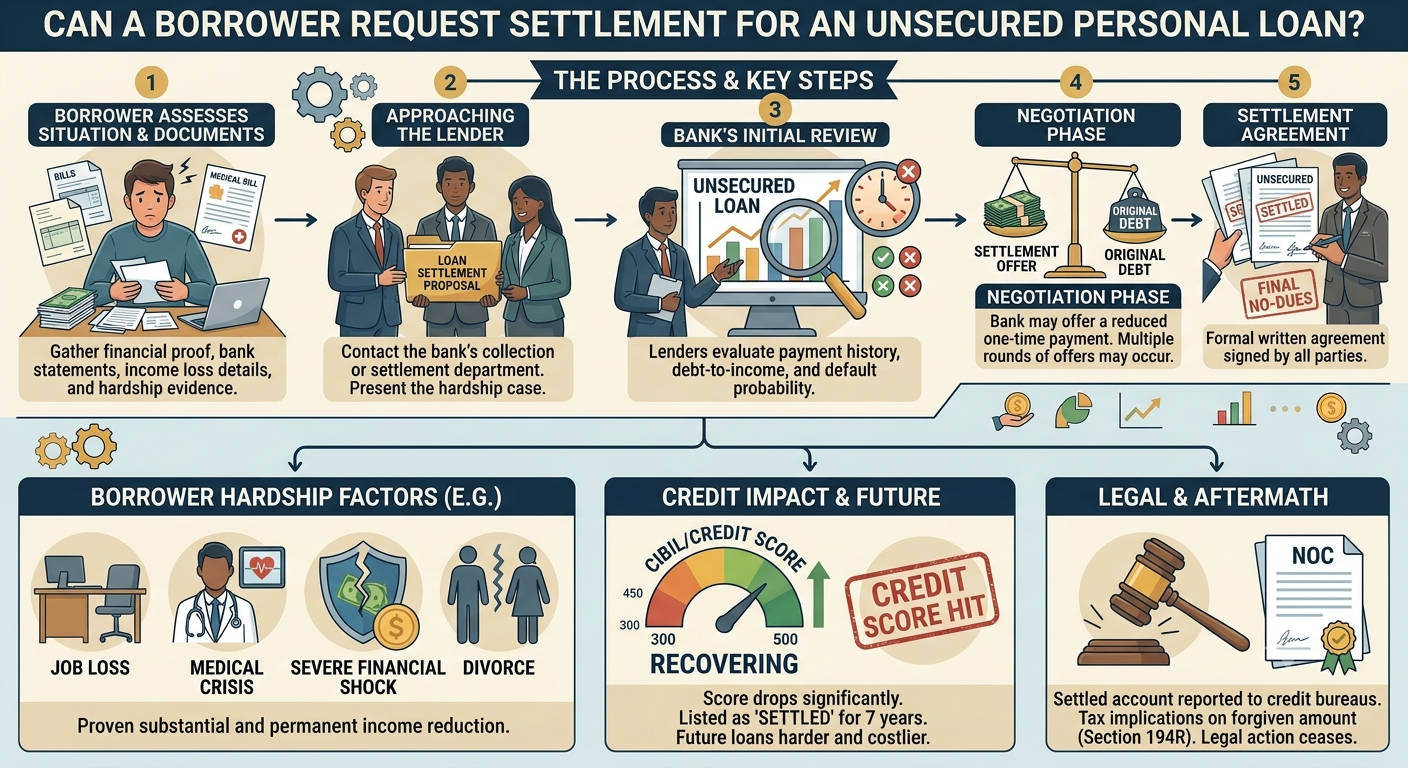
Unsecured personal loans provide quick liquid capital without requiring asset collateral like real estate or gold. However, when unexpected financial crises strike—such as sudden unemployment, medical emergencies, or severe business downturns—maintaining fixed Equated Monthly Installments (EMIs) becomes impossible. When defaults persist, borrowers frequently ask: Can a borrower officially request a loan settlement for an unsecured personal loan?
The short answer is yes. Financial institutions and Non-Banking Financial Companies (NBFCs) regularly evaluate compromise requests for unsecured obligations. Understanding how the process works allows distressed borrowers to navigate negotiations safely and legally.
Why Lenders Enter Compromise Negotiations for Unsecured Loans
Unlike home or auto loans, unsecured personal loans lack underlying collateral. When an account defaults for extended periods, lenders face specific operational dynamics:
- Absence of Asset Liquidation Rights: Lenders cannot unilaterally seize or auction property to recover their funds without lengthy judicial proceedings.
- Escalating Legal Costs: Pursuing prolonged litigation or arbitration often costs financial institutions more than accepting a discounted lump-sum compromise.
- Non-Performing Asset (NPA) Provisions: Regulations require lenders to set aside capital provisions for defaulted loans (NPAs) past 90 days. Approving a compromise resolution allows banks to clear toxic debt off their balance sheets.
Key Eligibility Criteria for Personal Loan Settlement
Lenders do not grant compromise approvals automatically. Bank credit committees evaluate applications against specific criteria to verify genuine distress:
- Documented Financial Hardship: Borrowers must provide objective proof of cash flow collapse, such as termination letters, hospital bills, or closed business accounts.
- Continuous Default Duration: Compromise requests are primarily considered after an account reaches Non-Performing Asset (NPA) status (90+ days overdue).
- Demonstrated Lump-Sum Payment Capacity: Lenders require confirmation that the borrower can remit the negotiated one-time settlement payment within an agreed timeframe.
Personal Loan Restructuring vs. One-Time Compromise Settlement
| Parameter | Personal Loan Restructuring | One-Time Loan Settlement (OTS) |
| Primary Objective | Extends loan tenure to reduce monthly EMI amounts | Waives accrued charges and reduces total balance |
| Financial Eligibility | Requires continuous, verified monthly income | Applicable during severe, prolonged financial default |
| Out-of-Pocket Cost | Increases overall interest paid over time | Secures a lump-sum discount on total outstanding debt |
| Credit Report Notation | Marked as “Restructured” on credit profiles | Marked as “Settled” on credit agency reports |
Crucial Steps to Follow When Requesting Settlement
If you decide to initiate compromise discussions with your bank, follow a structured framework to protect your legal position:
- Audit Total Claimed Dues: Request a detailed account statement to separate original principal balances from inflated penal interest and late fees.
- Prepare Hardship Records: Compile clear, verifiable evidence explaining why ongoing EMI payments are impossible.
- Formulate a Realistic Settlement Offer: Present an affordable one-time payment amount based on available emergency funds.
- Demand Official Written Sanction: Never make payments based on verbal promises. Always insist on a formal Settlement Sanction Letter printed on bank letterhead.
Navigating Unsecured Settlement with Professional Advice
Managing negotiations directly with institutional recovery officers while enduring financial hardship can feel overwhelming. Partnering with accredited advisers ensures your financial condition is presented effectively and negotiated within regulatory guidelines.
Engaging an established loan settlement agency provides immediate defense against harassing collection tactics. A professional loan settlement agency channels all official communications, handling recovery managers and legal notices on your behalf.
Utilizing specialized loan settlement services guarantees a thorough audit of accumulated charges. Comprehensive loan settlement services eliminate unjust penal interest and secure optimal principal discount terms.
Consulting an experienced loan settlement expert strengthens your representation before bank credit committees. An accredited loan settlement expert evaluates your debt profile, protects your rights under Reserve Bank of India (RBI) regulations, and negotiates practical settlement terms.
Executing a structured loan settlement grants legal release from spiraling financial liabilities. Once the agreed loan settlement amount is remitted directly to the lender, you receive a formal No Dues Certificate (NDC), ending all recovery actions permanently.
If personal loan EMIs are placing severe pressure on your budget, seeking a strategic loan settlement offers a proven path forward. Working alongside a qualified loan settlement expert and utilizing dedicated loan settlement services allows you to resolve your unsecured debt safely and rebuild your financial independence.
Requesting a settlement for an unsecured personal loan is a legitimate option for borrowers experiencing genuine hardship. By backing your proposal with verifiable financial proof, requiring written sanction letters, and seeking professional guidance, you can resolve your debts safely and secure long-term financial stability.