
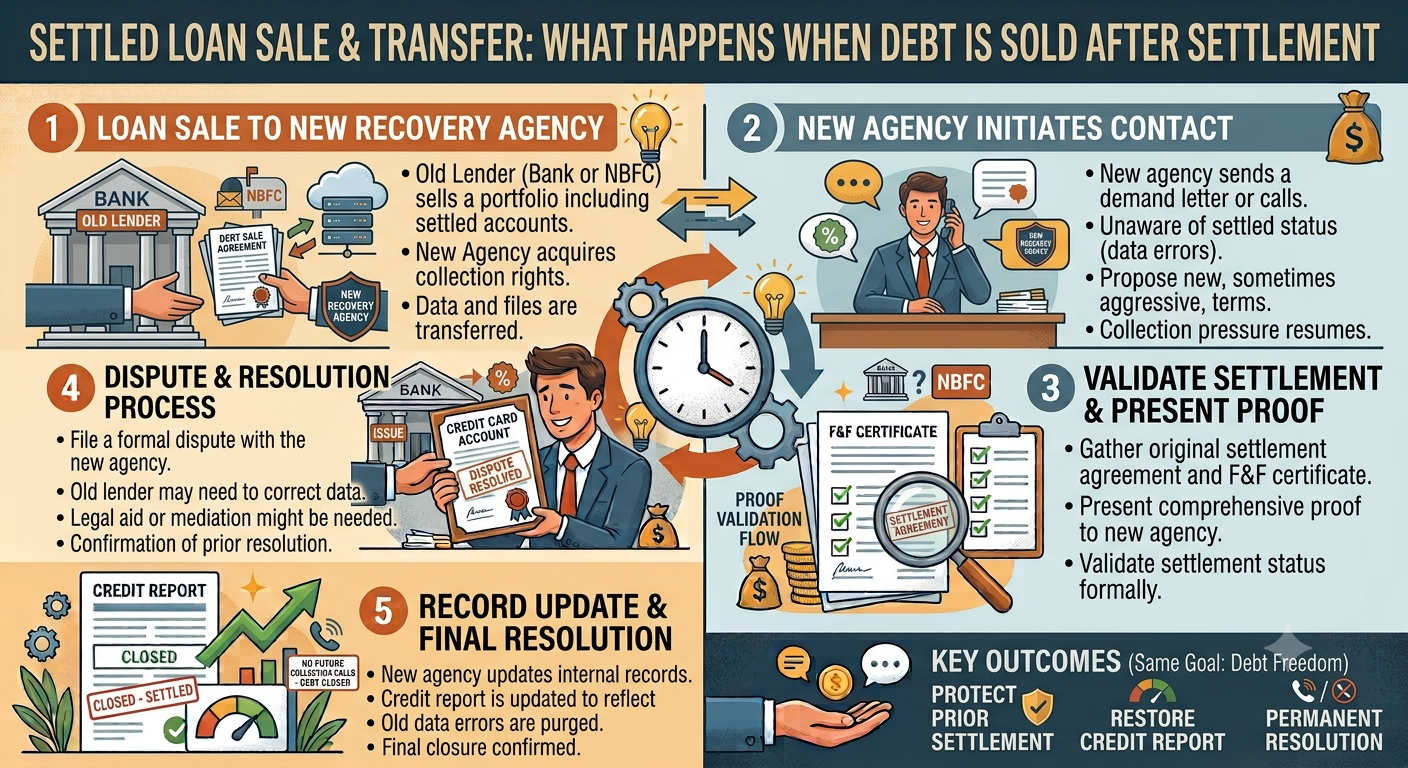
Resolving a defaulted loan through a One-Time Settlement (OTS) is a huge relief. However, many borrowers face a distressing surprise months or years after completing their settlement: receiving aggressive recovery calls, legal notices, or payment demands from a brand-new debt recovery agency or Asset Reconstruction Company (ARC) claiming that the debt was transferred or sold.
If you have already settled your account and received official discharge documentation, a recovery agency cannot legally force you to pay the debt again.
Understanding why these portfolio transfers occur and how to legally shield yourself against secondary recovery claims is essential to protecting your financial freedom.
Why Settled Loans Get Transferred to Recovery Agencies
To understand how a settled loan ends up in a third-party recovery portfolio, you need to look at how banking debt assignments work behind the scenes:
+-------------------------------------------------------------------------------+
|                       DEBT PORTFOLIO TRANSFER WORKFLOW                        |
+-------------------------------------------------------------------------------+
| 1. Bank Write-Off  --> Lenders sell bulk default portfolios (NPAs) to ARCs.   |
| 2. Data Mismatch   --> Settled accounts mistakenly remain in active ledgers.  |
| 3. Agency Assignment -> Third-party recovery agencies purchase old portfolios.|
| 4. Illegal Demand  --> Agency contacts borrower using outdated master files.   |
+-------------------------------------------------------------------------------+
- Bulk Debt Portfolio Sales: Banks and NBFCs periodically bundle write-off accounts, bad loans, and Non-Performing Assets (NPAs) into bulk portfolios and sell them to ARCs or collection agencies at a steep discount.
- Administrative Ledger Errors: If the original lender fails to update its internal master ledger after completing your settlement, your account data remains flagged as “Active Unpaid Debt” in the system.
- Automated Secondary Assignment: When the bank sells the debt portfolio, your settled account file is inadvertently passed along to the purchasing recovery agency, which then initiates recovery actions based on outdated files.
Your Legal Rights Under RBI Debt Assignment Guidelines
According to guidelines set by the Reserve Bank of India (RBI), debt assignment and recovery practices are governed by strict regulatory frameworks:
- Extinction of Right to Recover: Once an official Settlement Sanction Letter is issued and payment is completed according to agreed terms, the original debt obligation is legally extinguished. The lender no longer owns a valid debt claim to assign or sell to a third party.
- Protection Against Harassment: Third-party recovery agents cannot threaten, harass, or demand payments for legally discharged debts. Falsely demanding money for a settled loan violates the RBI Fair Practices Code for Lenders.
- Data Accuracy Mandate: Lenders are legally required to maintain accurate data across credit registries (such as CIBIL, Experian, High Mark, and Equifax) and update account statuses correctly after receiving full settlement payments.
Step-by-Step Action Plan: How to Stop Secondary Recovery Demands
If a new recovery agency contacts you regarding a previously settled loan, take these immediate legal and procedural steps to shut down their claim:
Step 1: Demand Written Proof of Claim
Never negotiate or discuss financial terms over the phone. Politely inform the collection agent that the debt was legally settled with the original lender. Request that they send all formal communications, demand notices, and proof of assignment in writing.
Step 2: Present Your Discharge Documentation
Provide the recovery agency with copies (never hand over original documents) of these three vital records:
- The original Settlement Sanction Letter issued by the primary lender.
- Payment Receipts / Bank Statements proving full deposit of the settled sum on or before the due date.
- The official No Dues Certificate (NDC) or Discharge Letter provided by the bank.
Step 3: Issue a Formal Cease and Desist Legal Notice
If the collection agency continues making recovery calls or doorstep visits after receiving your proof of settlement, send a formal legal notice through your legal counsel directing them to cease all harassment immediately.
Step 4: Escalate to the Banking Ombudsman & RBI Nodal Officer
If the original bank failed to update its master database and illegally assigned a settled account, file an official grievance with the bank’s Principal Nodal Officer. If unresolved within 30 days, escalate the matter directly to the RBI Integrated Ombudsman.
Essential Comparison: Active Debt Sale vs. Settled Debt Transfer
| Parameter | Active Unpaid Debt Sale | Settled Debt Transfer (Error) |
| Legal Validity of Claim | Legally Enforceable | Legally Void & Invalid |
| Borrower Liability | Balance owed to new ARC/Agency | Zero Liability (Fully Discharged) |
| Required Action | Negotiate compromise settlement | Present NDC & Issue Legal Notice |
| Regulatory Recourse | Debt resolution / OTS | Grievance via RBI Ombudsman |
Key Resources for Loan Settlement Protection
Navigating recovery agency disputes, auditing old credit portfolios, and protecting yourself against illegal debt reassignment requires professional guidance. Explore these essential resources:
- Consult a certified loan settlement expert to review recovery agency notices and verify account status.
- Manage complex debt reassignment disputes and legal notices through dedicated loan settlement services.
- Learn how to secure valid discharge letters using complete loan settlement guides.
- Shield yourself against illegal recovery harassment by partnering with an established loan settlement agency.
- Examine debt assignment validity alongside an accredited loan settlement expert.
- Escalate bank database errors and illegal portfolio sales using specialized loan settlement services.
- Stop third-party agency harassment supported by a trusted loan settlement agency.
- Understand RBI fair practice guidelines and debt transfer laws with expert loan settlement counsel.
- Protect your legal rights during debt portfolio transfers with direct help from a skilled loan settlement expert.
- Obtain institutional representation and direct Ombudsman escalation via dedicated loan settlement services.
- Ensure permanent credit bureau updates and legal closure with assistance from a reputable loan settlement agency.
Final Thoughts
A transferred or sold loan that has already been legally settled carries zero financial liability. By maintaining complete records of your Settlement Sanction Letter, payment receipts, and No Dues Certificate, you can quickly dismantle invalid recovery demands. Taking prompt legal action ensures your settled debt remains permanently closed.