
Falling into a credit card debt trap is one of the most financially draining experiences a borrower can face. Unlike traditional term loans with fixed monthly EMIs, credit cards carry compounding interest rates that can exceed 36% to 42% annually.
When you default or miss consecutive monthly payments, credit card issuers rapidly slap on late payment fees, over-limit charges, processing penalties, and Finance Charges. Within months, your original debt can double or triple.
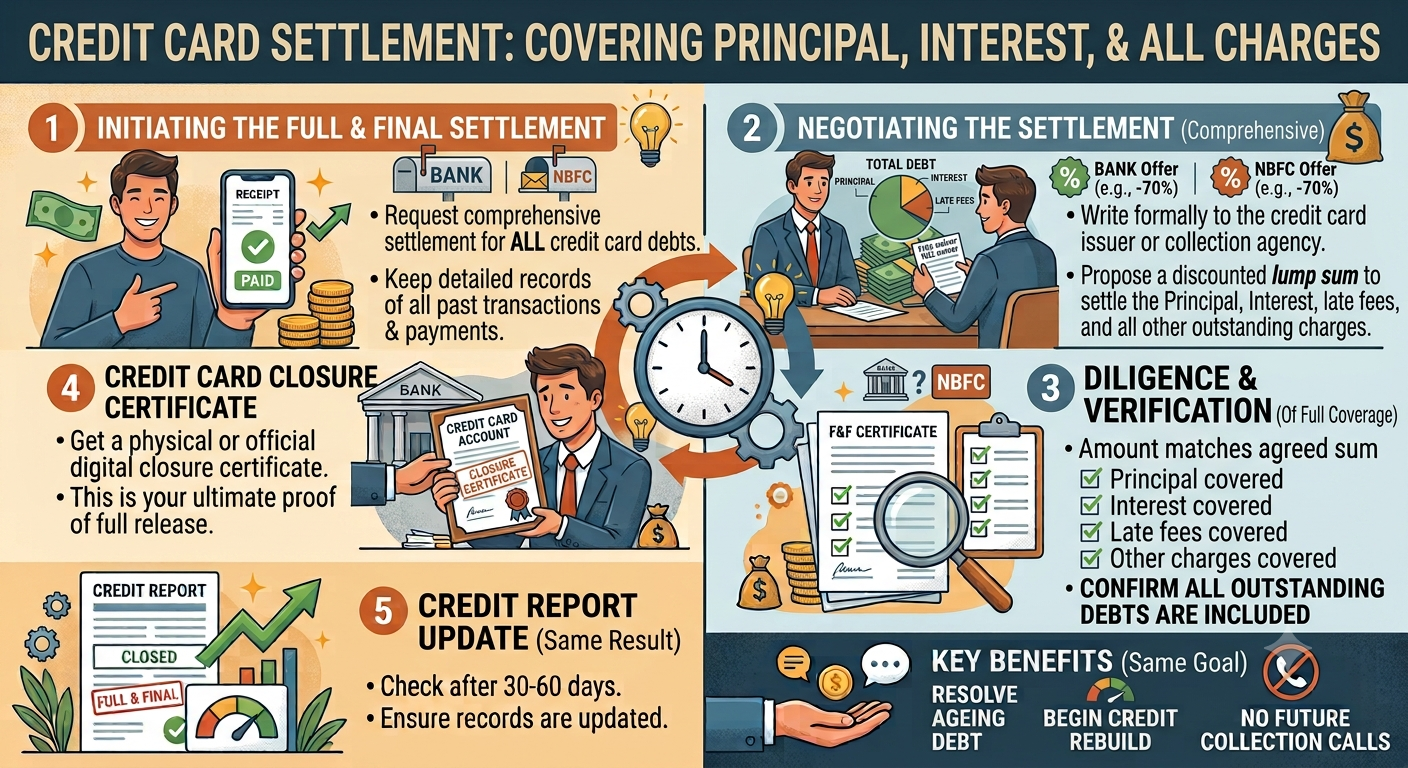
If you are struggling under overwhelming credit card debt, a critical question arises: Can a credit card settlement cover the original principal, accumulated interest, and all other outstanding charges?
The short answer is yes. A negotiated One-Time Settlement (OTS) can address all three components of your outstanding credit card balance. However, understanding how banks structure debt breakdowns is key to maximizing your savings.
Understanding the 3 Layers of Credit Card Debt
To negotiate effectively, you must understand how bank credit card statements divide your total balance into three distinct layers:
+-------------------------------------------------------------------------------+
|                      CREDIT CARD DEBT STRUCTURE & WAIVER PRIORITY              |
+-------------------------------------------------------------------------------+
| Layer 3: Penal Fees & Over-Limit Charges  --> 100% Waived First               |
| Layer 2: Accumulated Finance Interest     --> 100% Waived Second              |
| Layer 1: Core Principal Purchases/EMIs    --> Negotiated Base Discount (20-50%)|
+-------------------------------------------------------------------------------+
- Layer 1: Core Principal: The actual money spent on card purchases, retail transactions, cash withdrawals, or active EMI conversions.
- Layer 2: Accumulated Interest: Compounding monthly finance charges applied to unpaid balances since the default date.
- Layer 3: Penalties & Other Charges: Late payment fees, NACH/PDC bounce charges, over-limit penalties, and applicable GST/taxes.
How Settlement Waives Principal, Interest, and Penalties
When a credit card account remains unpaid past 90 days, the bank classifies it as a Non-Performing Asset (NPA). Credit card debt is completely unsecured, meaning the bank holds no asset or physical collateral to seize and sell.
Because recovering unsecured credit card debt through lengthy civil litigation is costly, credit card issuers are incentivized to negotiate compromise settlements.
Here is how each layer is treated during a formal settlement negotiation:
1. 100% Waiver on Penalties and Other Charges (Layer 3)
In almost every credit card settlement, banks agree to completely eliminate late payment fees, over-limit charges, and bounce fees. These artificial penalties cost the bank nothing in primary funds, making them the easiest items to strike off during initial discussions.
2. 100% Waiver on Accumulated Interest (Layer 2)
The compounding finance charges applied after your default date are routinely written off during OTS negotiations. The bank’s primary recovery objective is to collect a portion of the real funds advanced rather than uncollected interest margins.
3. Negotiated Discount on Core Principal (Layer 1)
Once all interest and penalty charges are waived, negotiations move to the core principal amount. Depending on your proven level of financial hardship (such as job loss, medical emergencies, or business failure), banks may offer a 20% to 50% discount on the original principal balance.
Critical Steps to Ensure Complete Debt Discharge
To ensure your credit card settlement covers all outstanding balances without leaving residual claims, follow these essential steps:
- Request an Official Statement of Account (SOA): Obtain an itemized statement showing the exact breakdown of principal versus penal charges before making any settlement offer.
- Submit Hardship Documentation: Provide objective proof of financial distress—such as salary cut slips, medical bills, or bank statements—to justify your inability to repay the full balance.
- Insist on an Official Sanction Letter: Never deposit settlement funds based on verbal assurances or WhatsApp messages from recovery agents. Demand an official Settlement Sanction Letter on bank letterhead confirming that the payment clears all principal, interest, and penalties in full.
- Verify Zero Balance in Your NDC: After making the agreed payment, obtain an official No Dues Certificate (NDC) from the bank confirming zero outstanding liability across all charges.
Total Balance Payment vs. One-Time Settlement
| Parameter | Full Total Balance Payment | One-Time Credit Card Settlement |
| Penal Fees & Charges | Paid in full | 100% Waived |
| Accumulated Interest | Paid in full | 100% Waived |
| Principal Amount | Paid in full | Discounted (20% to 50% Off) |
| Out-of-Pocket Cost | High (100% of inflated debt) | Significantly lower lump sum |
| Credit Bureau Status | Marked “Closed / Paid in Full” | Marked “Settled” with Zero Balance |
Key Resources for Credit Card Settlement
Navigating credit card desk negotiations, auditing statement charges, and securing written sanction letters requires specialized expertise. Use these resources to guide your debt resolution:
- Evaluate your eligibility for full interest and fee waivers with a certified loan settlement expert.
- Explore structured compromise solutions for high-balance credit cards via loan settlement services.
- Learn how to calculate realistic settlement percentages using complete loan settlement guides.
- Protect yourself from aggressive recovery tactics by partnering with a trusted loan settlement agency.
- Review your credit card statements and penal charges alongside an accredited loan settlement expert.
- Eliminate late fees and negotiate core principal discounts using specialized loan settlement services.
- Manage legal notices and recovery calls supported by an established loan settlement agency.
- Understand bank settlement guidelines and RBI regulations with expert loan settlement advice.
- Safeguard your legal rights and resolve credit card debt with direct support from a skilled loan settlement expert.
- Obtain institutional representation and direct bank escalation via dedicated loan settlement services.
- Secure your official No Dues Certificate (NDC) and full legal discharge with help from a reputable loan settlement agency.
Final Thoughts
A well-negotiated credit card settlement can cover the core principal, accumulated interest, and all secondary penal charges. By auditing your credit card statement, establishing proven financial hardship, securing an official sanction letter, and obtaining a No Dues Certificate, you can permanently eliminate your credit card debt and reclaim control of your financial future.