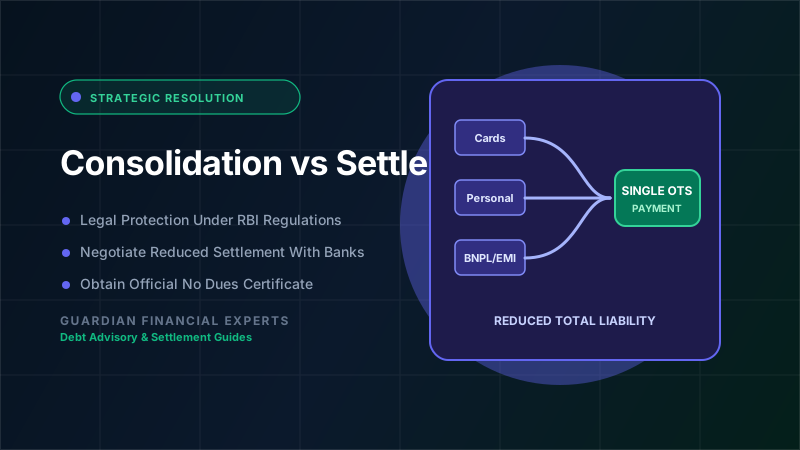
If you're unable to pay EMIs, you have two major options:
- Settle Loan
- Restructure Loan
But which one is better?
This detailed comparison helps you choose the best option based on your financial health.
1. What Does It Mean to Settle Loan?
Loan settlement means:
- You pay a reduced amount
- Remaining balance is waived
- Loan is closed as “settled”
Recommended when:
✔ You cannot pay EMIs
✔ Your income has dropped
✔ Legal action has begun
✔ You have multiple unsecured loans
Read full loan settlement process:
https://guardianfinancialexperts.com/lss.html
2. What Is Loan Restructuring?
Restructuring means:
- EMI is reduced
- Tenure is extended
- Loan is not closed
- Interest may increase
Recommended when:
✔ You have temporary financial issues
✔ You want to keep your CIBIL clean
✔ You can pay reduced EMIs
RBI restructuring circulars:
https://www.rbi.org.in/Scripts/NotificationUser.aspx
3. Comparison Table
| Feature | Settle Loan | Restructure Loan |
|---|---|---|
| EMI Continues? | ❌ No | ✔ Yes |
| CIBIL Impact | ✔ Negative | ❌ Minimal |
| Best For | Severe hardship | Temporary issues |
| Legal Risk | Reduced | Delayed |
| Savings | High | Low |
| Approval Difficulty | Moderate | High |
4. When Should You Choose Settlement?
Choose settlement if:
- Your debt is unmanageable
- You are receiving recovery calls
- Penalties have doubled
- Income is unstable
Contact Settlement Experts:
https://guardianfinancialexperts.com/contact.html
5. When Should You Choose Restructuring?
Choose restructuring if:
- You expect recovery soon
- Want to protect CIBIL
- Only need breathing room
6. Impact on CIBIL Score
Settlement affects CIBIL temporarily.
Check your score here:
https://www.cibil.com/credit-score
You can rebuild it in 6–18 months through:
https://guardianfinancialexperts.com/csbp.html
Conclusion
Choose settle loan when your financial situation is severe.
Choose restructuring when your issue is temporary.
For expert evaluation of your case:
https://guardianfinancialexperts.com/contact.html
Explore Bank-Specific Resolution & Debt Relief Services
Facing debt recovery notices, escalating interest, or multiple EMI defaults? Navigate our authoritative settlement guides and legal resolution procedures tailored for Indian borrowers:
HDFC Bank Loan Settlement
Personal loan & credit card OTS procedures, waiver rules, and recovery resolution.
SBI Loan Settlement Process
State Bank of India compromise settlement, NPA resolution, and Lok Adalat guidelines.
ICICI Bank Loan Settlement
Resolution for overdue credit cards, personal loans, and third-party recovery defense.
Bajaj Finance Debt Settlement
NBFC overdue loan settlement, bounce charges negotiation, and NDC documentation.
Credit Card Settlement Services
Stop 40%+ compounding APR and settle high-balance credit cards with structured waivers.
Personal Loan Settlement
Resolve multiple unsecured loans, fintech apps, and salary defaults with legal protection.
Anti-Harassment Legal Support
Enforce RBI fair practice code to halt abusive recovery calls, threats, and illegal visits.
CIBIL & Credit Score Improvement
Step-by-step roadmap to rebuild credit rating from 'Settled' status back to 750+.
Every loan case is unique. If you are experiencing EMI pressure or receiving recovery notices, our team is available for a confidential consultation.