
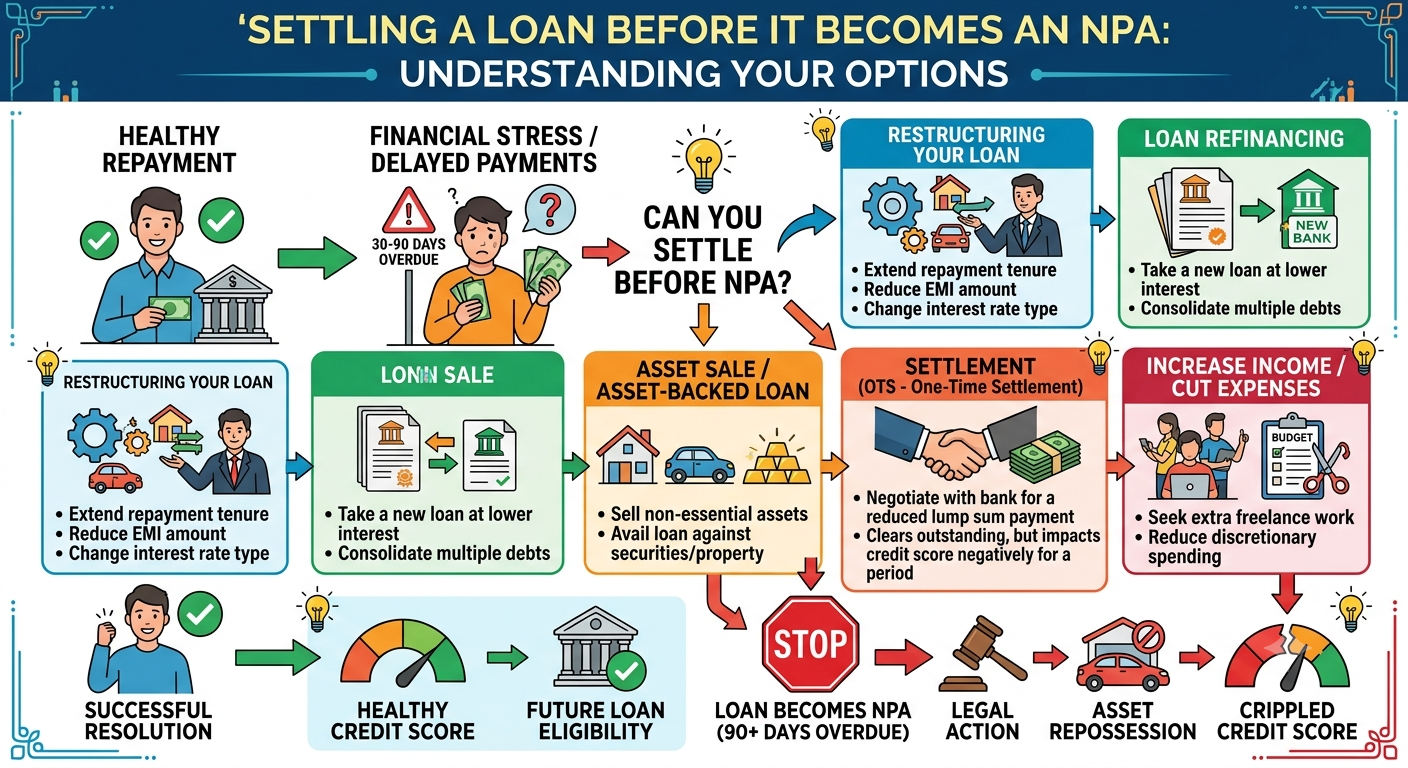
When unexpected financial crises arise—such as severe job loss, sudden medical emergencies, or a sharp downturn in business revenue—servicing high Equated Monthly Installments (EMIs) becomes an immediate operational challenge. Most borrowers are aware that missing payments for more than 90 days causes banks to declare an account a Non-Performing Asset (NPA). However, sitting idle while watching debt compound over three months creates severe financial stress. This raises a critical question: Can you settle a loan before it officially becomes an NPA?
The short answer is yes. While banking institutions typically initiate formal compromise settlements after an account enters NPA status, proactive borrowers facing genuine financial hardship can negotiate early resolution pathways under regulatory guidelines. Understanding how pre-NPA resolution works helps you protect your financial standing and halt spiraling interest charges early.
Understanding the Pre-NPA Timeline: SMA Categories
Before a loan account is classified as an NPA, it passes through preliminary default stages known as Special Mention Accounts (SMA) under Reserve Bank of India (RBI) standards:
- SMA-0 (1 to 30 Days Overdue): The first missed EMI triggers automated payment reminders, late payment fees, and initial penal interest charges.
- SMA-1 (31 to 60 Days Overdue): Persistent non-payment leads to intensive follow-up communications and negative default reporting to credit bureaus like CIBIL.
- SMA-2 (61 to 90 Days Overdue): The final pre-NPA window where lending institutions flag the account for imminent asset classification downgrade and potential legal recovery procedures.
Initiating discussions with your lender during the SMA stages—rather than waiting for full NPA status—demonstrates good faith and opens doors to early debt management mechanisms.
Practical Pre-NPA Financial Options for Struggling Borrowers
If you foresee an inability to resume regular EMI payments, several proactive options exist before full account default occurs:
- Requesting a Temporary Moratorium: Banks may offer a payment deferment of 3 to 6 months if you provide proof of temporary financial hardship, giving you breathing room to secure new income without accruing immediate penal escalation.
- Loan Restructuring and Tenor Extension: Lenders can extend your overall repayment period, significantly reducing your monthly EMI burden so it matches your current reduced cash flow.
- Early One-Time Settlement (OTS) Negotiations: If long-term recovery is unviable, borrowers can propose an early compromise settlement. While banks prefer full recovery during early SMA stages, proving total insolvency can persuade credit committees to accept a pre-NPA lump-sum closure.
Pre-NPA Financial Resolution Option Matrix
| Resolution Pathway | Target Stage | Immediate Financial Benefit | Impact on Credit Profile |
| EMI Deferment / Moratorium | SMA-0 / SMA-1 | Pauses monthly payment pressure | Minimal impact if approved formally |
| Loan Tenor Restructuring | SMA-1 / SMA-2 | Lowers monthly EMI outflow | Updated repayment terms on bureau |
| Pre-NPA One-Time Settlement | SMA-2 | Permanent debt discharge via lump sum | Account marked as settled with zero liability |
Navigating Pre-NPA Settlement Through Professional Representation
Negotiating with banking authorities before an account reaches NPA classification requires strategic presentation and strict legal compliance. Lenders are naturally hesitant to offer waivers on active accounts, making expert representation invaluable.
Partnering with an established loan settlement agency provides structural guidance when dealing with credit risk departments. A professional loan settlement agency handles complex legal correspondence, shields you from aggressive collection tactics, and presents your case accurately to bank officials.
Utilizing specialized loan settlement services ensures that your financial hardship is documented in full alignment with RBI regulations. Experienced loan settlement services analyze your total liabilities, challenge excessive penal interest additions, and structure an affordable compromise package tailored to your capacity.
Consulting an accredited loan settlement expert helps build a compelling case for early account resolution. A qualified loan settlement expert negotiates directly with bank credit committees to secure maximum waivers on interest and principal amounts before legal notices escalate.
Executing an early loan settlement halts financial decay before severe legal actions commence. Once an agreed loan settlement sum is paid, the bank issues a formal Settlement Sanction Letter followed by a No Dues Certificate (NDC), permanently closing the debt file.
If you are struggling during the pre-NPA stage, seeking a tailored loan settlement prevents further compounding of unmanageable debt. Working alongside a dedicated loan settlement expert safeguards your rights, while comprehensive loan settlement services allow you to achieve debt relief and rebuild your financial independence.
Settling a loan before it becomes an NPA is challenging, but entirely achievable with prompt action and proper strategy. By understanding your options early, gathering proof of hardship, and engaging professional guidance, you can resolve your obligations smoothly and secure a fresh financial start.