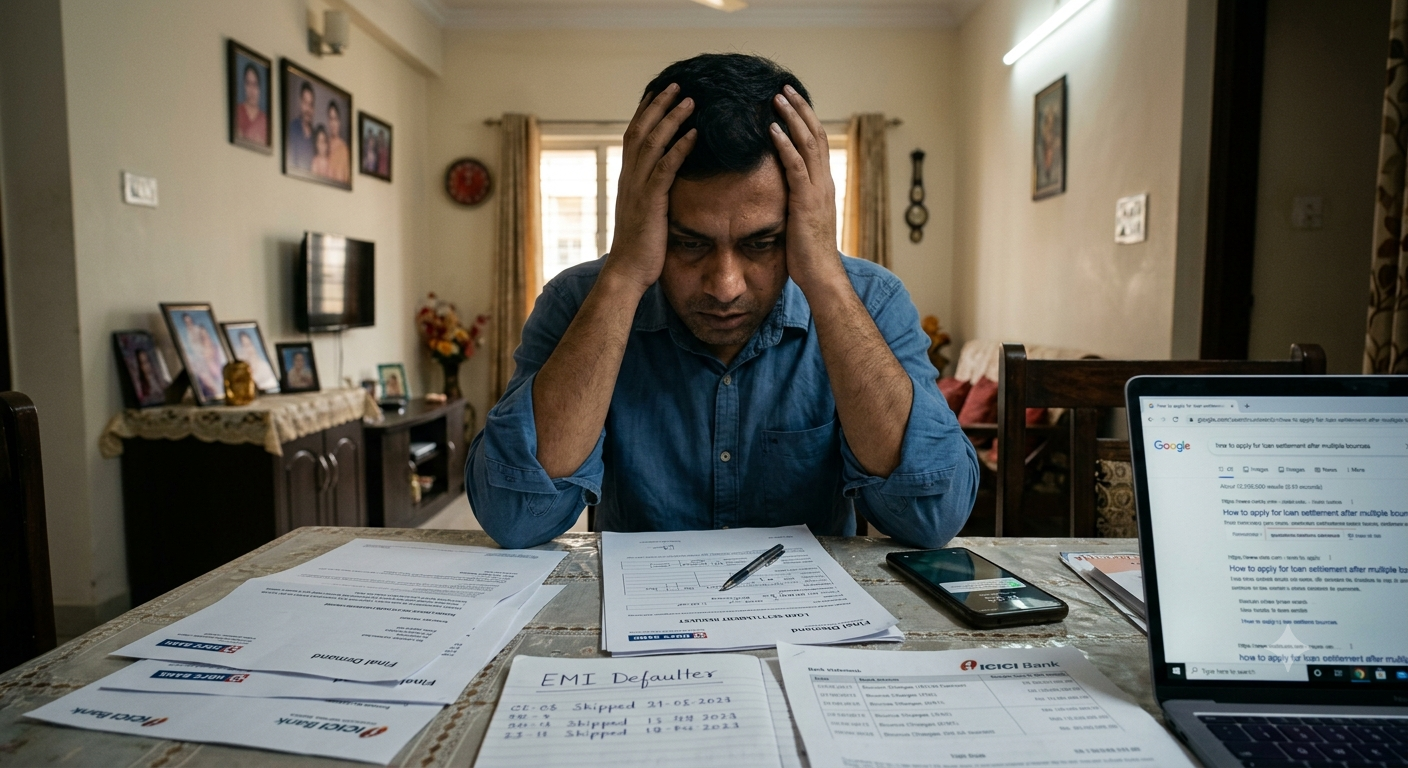
Experiencing multiple EMI bounces on a personal loan, home loan, credit card, or business loan is one of the clearest warning signs of severe financial distress. When income drops, unexpected medical emergencies arise, or business revenues plummet, keeping up with monthly debt obligations becomes unsustainable.
If you have defaulted on multiple consecutive installments, a critical question arises: Can you still request a loan settlement after several EMI bounces?
The short answer is yes. In fact, defaulting on several EMIs is often the exact stage at which banks and Non-Banking Financial Companies (NBFCs) become open to negotiating a One-Time Settlement (OTS).
What Happens After Multiple EMI Bounces?
When you miss EMI payments, banks follow a structured escalation process dictated by banking guidelines and credit risk frameworks:
+-------------------------------------------------------------------------------+
|                    LOAN DEFAULT & ESCALATION TIMELINE                         |
+-------------------------------------------------------------------------------+
| Stage 1: 1–30 Days Past Due (DPD)   --> Payment Reminders & Bounce Charges   |
| Stage 2: 31–80 Days Past Due (DPD)  --> Collection Calls & Soft Recovery      |
| Stage 3: 90 Days Past Due (DPD)     --> Account Classified as NPA             |
| Stage 4: 90+ Days Past Due (DPD)    --> Legal Notices & Settlement Eligibility|
+-------------------------------------------------------------------------------+
- SMA-0, SMA-1, and SMA-2 Classification: During the first 90 days of missed payments, your account is flagged under Special Mention Account (SMA) categories, triggering penal interest and collection reminders.
- NPA Classification (at 90 Days): Once an account reaches 90 days past due (3 consecutive EMI bounces), the lender classifies the account as a Non-Performing Asset (NPA).
- Provisioning Requirements: After an account becomes an NPA, banks are required to set aside capital provisions to cover potential losses. To recover tied-up funds, lenders prefer negotiating a compromised settlement over lengthy litigation.
Why Lenders Agree to Settlement After EMI Bounces
From the lender’s perspective, an account with multiple bounced EMIs indicates a high risk of total loss. Carrying uncollected debt indefinitely incurs high recovery costs, legal expenses, and regulatory pressure.
Lenders become willing to negotiate a settlement after several bounces because:
- Capital Recovery: Recovering a guaranteed 40% to 60% lump-sum payment immediately is financially better for the bank than writing off 100% of the loan.
- Cost Reduction: Continuing recovery calls, sending legal notices, or initiating court proceedings costs time and money.
- Balance Sheet Cleanup: Settling NPA accounts helps banks clear bad loans from their books during quarter-end or year-end closing cycles.
Risks to Keep in Mind After EMI Bounces
While requesting a settlement after multiple bounced EMIs is entirely possible, you must navigate several crucial legal and financial risks:
- Legal Notices: Multiple bounced EMIs can lead to legal action under Section 138 of the Negotiable Instruments Act (cheque bounce) or Section 25 of the Payment and Settlement Systems Act (NACH/e-Mandate default).
- Impact on CIBIL Score: EMI defaults cause immediate drops in your credit score. Settling the account will mark it as “Settled” in bureau records rather than “Closed.”
- Penal and Bounce Fees: Banks stack heavy penal interest and ECS bounce charges on default balances, which should be negotiated down during settlement talks.
Key Comparison: Restructuring vs. Settlement After Default
| Parameter | Loan Restructuring | One-Time Settlement (OTS) |
| Account Eligibility | Early stage or pre-NPA | Post-NPA (3+ EMI bounces) |
| Total Payable Amount | Full principal + interest (extended tenure) | Reduced lump-sum amount (discounted) |
| Credit Report Impact | Marked as “Restructured” | Marked as “Settled” |
| Legal Proceedings | Suspended/Not initiated | Withdrawn upon full settlement payment |
Key Resources for Navigating Settlement After EMI Default
Handling legal notices, negotiating with recovery officers, and securing written sanction letters after several EMI defaults requires strategic planning and legal experience. Explore these specialized resources for assistance:
- Evaluate your eligibility for an NPA compromise by consulting a certified loan settlement expert.
- Stop aggressive recovery calls and handle default notices through structured loan settlement services.
- Learn how to negotiate principal waivers after multiple defaulted EMIs with complete loan settlement advice.
- Protect yourself from legal action under Section 138 by partnering with a reliable loan settlement agency.
- Review your loan statements and default penalties alongside a seasoned loan settlement expert.
- Secure formal settlement sanction letters and clear waivers through professional loan settlement services.
- Manage Debt Recovery Tribunal (DRT) filings and legal defenses supported by an experienced loan settlement agency.
- Understand bank NPA provisioning rules and negotiation windows with expert loan settlement guidance.
- Safeguard your assets and stop recovery harassment with help from a dedicated loan settlement expert.
- Structure manageable lump-sum repayment schedules using institutional loan settlement services.
- Achieve complete financial closure and obtain your No Dues Certificate through a trusted loan settlement agency.
Final Thoughts
If you have missed multiple EMIs and are struggling to keep up with your debt, you do not have to wait for legal action to escalate. Requesting a One-Time Settlement after several EMI bounces is a legitimate and widely used financial recovery mechanism.
By engaging directly with your lender, demonstrating genuine financial hardship, and securing a formal written settlement letter, you can settle your debt for a fraction of the total balance and take your first major step toward financial recovery.