When a borrower faces severe financial distress and defaults on loan Equated Monthly Installments (EMIs) or credit card payments, the total outstanding balance quickly balloons. Banks and Non-Banking Financial Companies (NBFCs) add compounding penal interest, overdue charges, cheque or NACH bounce fees, and late payment penalties. Within months, these extra charges can make repayment seem mathematically impossible.
If you are struggling with a defaulted loan, a crucial question arises: Can banks actually waive these penal charges during a One-Time Settlement (OTS)?
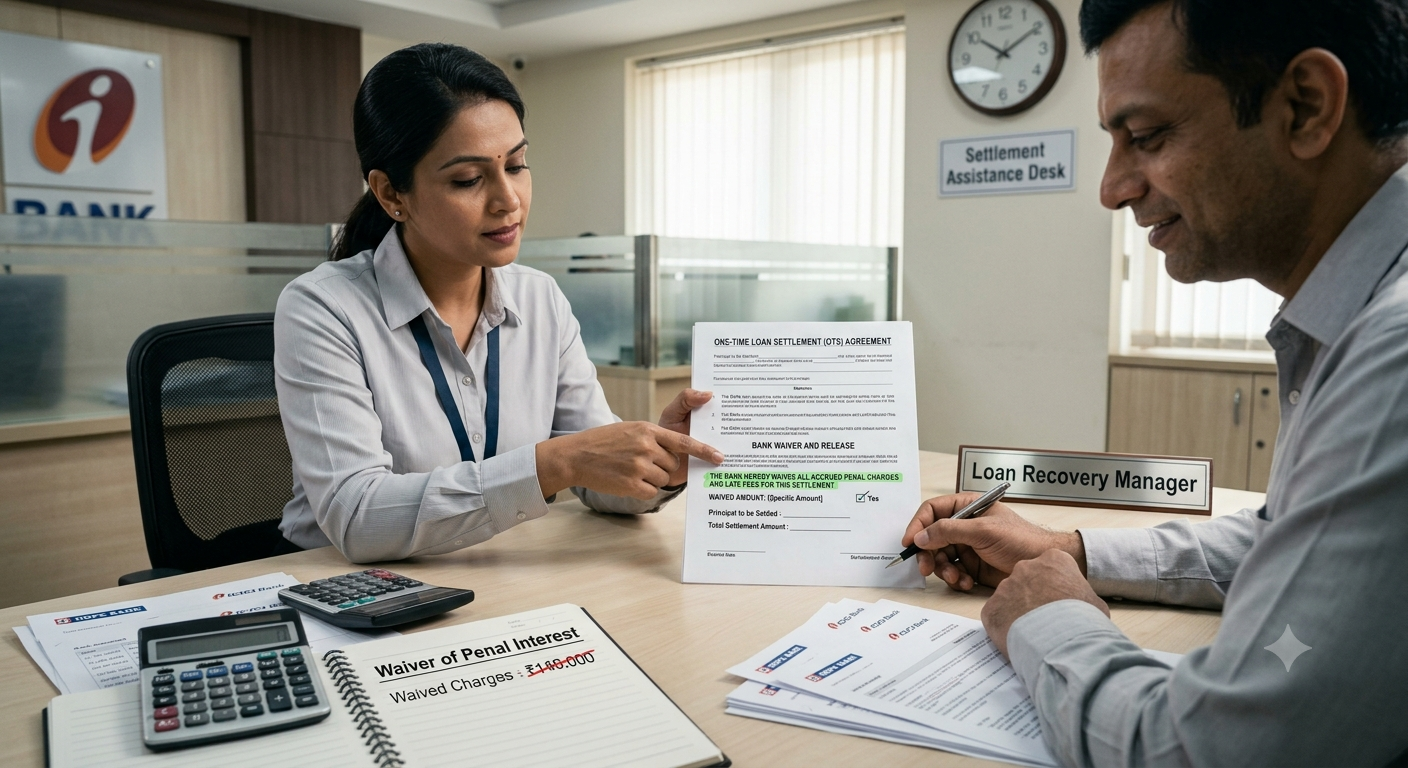
The short answer is a definitive yes. In fact, a complete waiver of accumulated penal charges and late fees forms the starting foundation of almost every negotiated loan settlement in India.
Understanding How Penal Charges Accumulate
To understand why banks are willing to drop penal fees, it helps to break down the total claim amount demanded by a lender into three distinct layers:
+-------------------------------------------------------------------------------+
|                    ANATOMY OF A DEFAULTED LOAN BALANCE                        |
+-------------------------------------------------------------------------------+
| Layer 1: Core Principal      | The actual borrowed capital remaining unpaid.  |
| Layer 2: Contracting Interest| Normal agreement interest accrued to default.  |
| Layer 3: Penal Fees & Charges| Compounding penal %, bounce fees, late charges.|
+-------------------------------------------------------------------------------+
Layer 3 (penal charges) consists of artificial accounting inflations imposed after default to encourage timely payments. When an account defaults past 90 days and is classified as a Non-Performing Asset (NPA), credit committees recognize that demanding these inflated penalties often prevents the borrower from paying anything at all.
As a result, banking regulations and internal credit policies allow lenders to eliminate Layer 3 entirely during compromise negotiations.
Which Penal Charges Can Be 100% Waived?
During a structured settlement negotiation, banks regularly grant full waivers on the following items:
- Penal Interest Rates: Additional interest percentages (often 2% to 3% per month) levied on overdue balances.
- Cheque / Auto-Debit Bounce Fees: Accumulated charges for failed NACH mandate or bounced cheque clearing attempts.
- Late Payment Charges: Fixed recurring administrative fines for missing monthly deadlines.
- Compounding Overhead: Interest calculated on top of accumulated unpaid penalties.
Beyond waiving 100% of these penal charges, banks frequently offer a discount on the core principal balance (often ranging between 20% and 60%), depending on the severity of the borrower’s documented hardship.
How to Request a Penal Charge Waiver
Banks rarely drop penal fees automatically—borrowers must formally request the waiver through structured negotiations:
1. Audit Your Statement of Account (SOA)
Obtain an official statement of account from your bank’s home branch or Principal Nodal Officer. Separate the core principal balance from accumulated penal charges and late fees.
2. Provide Verifiable Financial Hardship Proof
Lenders must comply with Reserve Bank of India (RBI) guidelines to ensure they are dealing with distressed borrowers rather than willful defaulters. Submit objective evidence—such as job termination letters, business loss statements, or medical bills—proving your default was involuntary.
3. Submit a Written Settlement Proposal
Draft a formal compromise offer proposing a realistic lump-sum payment toward the core principal while demanding a 100% waiver of all penal interest, bounce charges, and late fees.
4. Secure an Official Sanction Letter
Never make a settlement payment based on verbal assurances from recovery agents. Demand an official Settlement Sanction Letter printed on bank letterhead explicitly confirming the complete waiver of all penal charges and declaring the compromised payment as full and final satisfaction of the account.
Penal Charges: Standard Repayment vs. One-Time Settlement
| Parameter | Standard Repayment | One-Time Settlement (OTS) |
| Penal Interest & Late Fees | 100% Payable | 0% (100% Waived) |
| NACH / Cheque Bounce Fees | 100% Payable | 0% (100% Waived) |
| Principal Balance | 100% Payable | Discounted (30%–60% Waiver) |
| Credit Report Status | Marked “Closed” | Marked “Settled” |
Essential Resources for Penal Charge Waivers
Navigating bank credit committees, auditing statements of account, and securing maximum fee waivers requires specialized financial and legal expertise. Explore these essential resources for guidance:
- Evaluate your eligibility for penal charge waivers with a certified loan settlement expert.
- Explore tailored relief options for personal, business, and credit card debts through loan settlement services.
- Learn how to calculate realistic settlement waivers using complete loan settlement guides.
- Protect yourself from recovery harassment and unfair fees by partnering with a trusted loan settlement agency.
- Review your financial records and bank statements alongside an accredited loan settlement expert.
- Eliminate illegal bounce charges and negotiate principal waivers through specialized loan settlement services.
- Manage legal notices and bank communications supported by an established loan settlement agency.
- Understand RBI guidelines on debt compromise frameworks with professional loan settlement advice.
- Safeguard your assets and secure written discharge guarantees from a skilled loan settlement expert.
- Obtain institutional representation and documentation audits via professional loan settlement services.
- Achieve complete legal closure and secure your official No Dues Certificate (NDC) with an experienced loan settlement agency.
Final Thoughts
Accumulating penal charges and bounce fees can make defaulted debt feel insurmountable, but they should never prevent you from resolving your financial obligations. By presenting verified hardship documentation, negotiating through formal channels, and obtaining an official sanction letter, you can eliminate all penal charges and settle your debt safely.