
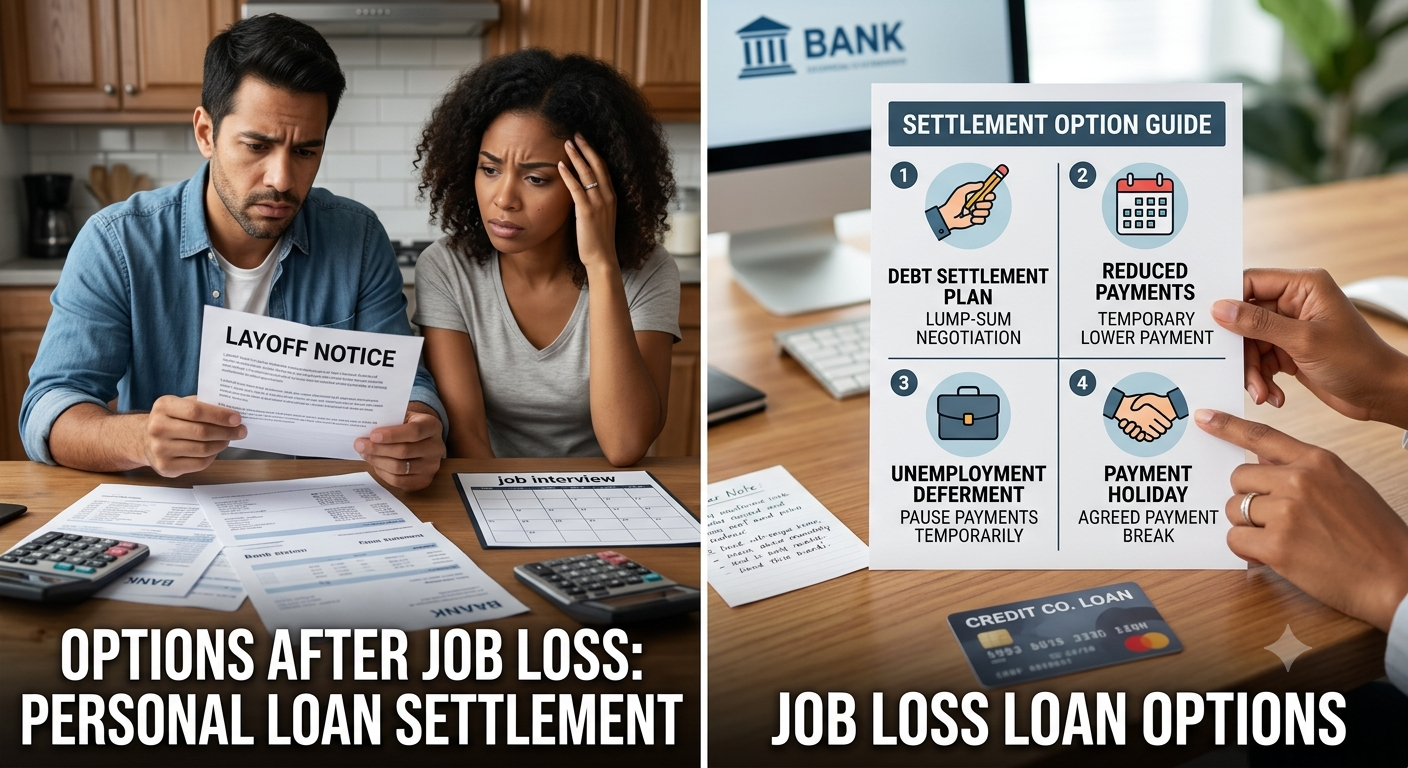
Experiencing an unexpected job loss or sudden layoff can turn your financial life upside down in an instant. When primary income halts, keeping up with fixed monthly Equated Monthly Installments (EMIs)—especially high-interest personal loan payments—can become impossible. Faced with dwindling savings, default risk, and collection pressure, borrowers often wonder what legal options exist to resolve personal debt safely.
Navigating a debt compromise after income disruption requires understanding bank procedures, regulatory safeguards, and strategic options available to distressed borrowers.
Step 1: Understand Your Legal & Operational Options
When income loss renders personal loan EMIs unpayable, borrowers generally have four distinct relief mechanisms available through financial institutions:
- Loan Restructuring: Requesting extended tenure to reduce monthly EMI amounts or converting existing obligations into longer-term loans.
- EMI Moratorium / Deferred Payment Window: Seeking a temporary pause in repayments (usually 3 to 6 months) while actively seeking new employment.
- Interest & Waiver Relief: Negotiating the removal of penal interest fees accumulated during early default months.
- One-Time Loan Settlement (OTS): Negotiating a compromise agreement to pay a single, reduced lump-sum amount to extinguish total outstanding debt permanently.
Step 2: Assemble Unassailable Proof of Involuntary Hardship
Financial institutions evaluate compromise applications based on clear proof that default is involuntary rather than intentional. To negotiate effectively, gather the following verification:
- Official Termination Documentation: Pink slips, formal lay-off emails, or corporate severance letters stating employment termination.
- Bank Account Statements: 3 to 6 months of bank cash-flow records showing the sudden stoppage of salary credits.
- Asset & Income Declaration: Proof showing lack of secondary liquid assets or immediate alternate income sources.
Key Resolution Strategies After Job Loss
| Relief Path | Primary Objective | Best Suited For | Credit Score Impact |
| Moratorium / EMI Pause | Temporary payment holiday | Short-term job gap (1–3 months) | Minimal / Neutral |
| Tenure Extension / Restructure | Lower monthly EMI commitment | Re-employed at lower income level | Minor impact |
| One-Time Loan Settlement | Discharge debt at reduced sum | Severe, prolonged unemployment | Marked as “Settled” |
Know Your Rights Under RBI Guidelines
Borrowers facing debt distress maintain strict consumer rights under Reserve Bank of India (RBI) guidelines:
- Fair Treatment by Recovery Agents: Agents are legally restricted from calling before 8:00 AM or after 7:00 PM, visiting without prior notification, or engaging in intimidation.
- Right to Formal Written Sanction: No settlement payment should ever be made without an official sanction letter issued directly on the bank’s letterhead.
- Entitlement to Closure Certification: Lenders are legally required to issue a No Dues Certificate (NDC) once sanctioned settlement funds are remitted.
Resolving Personal Debt Safely with Professional Support
Navigating complex negotiations with bank credit managers while handling personal employment stress can be overwhelming. Partnering with accredited financial advisors ensures your case is presented persuasively and within regulatory boundaries.
Engaging an established loan settlement agency provides an immediate buffer against collection pressure. A dedicated loan settlement agency manages all official communications, legal notices, and bank meetings on your behalf.
Utilizing specialized loan settlement services guarantees a thorough audit of accumulated charges. Comprehensive loan settlement services help eliminate unjustified penal interest and negotiate maximum principal discount terms.
Consulting a recognized loan settlement expert strengthens your standing before institutional credit committees. An accredited loan settlement expert evaluates your hardship documentation, safeguards your rights under consumer protection rules, and structures viable terms.
Executing a structured loan settlement brings legal closure to spiraling debt liabilities. Once the sanctioned sum is remitted, completing a formal loan settlement ensures you receive an official No Dues Certificate (NDC), halting recovery proceedings permanently.
If an unexpected job loss is making your loan obligations unmanageable, seeking a structured loan settlement offers a proven path forward. Working with an experienced loan settlement expert and utilizing trusted loan settlement services allows you to discharge your obligations safely and rebuild your financial independence.
Overcoming personal loan default after job loss requires proactive communication, documented proof, and disciplined negotiation. By securing official written sanction letters and leveraging expert advice, you can resolve your debts safely and secure long-term financial stability.