
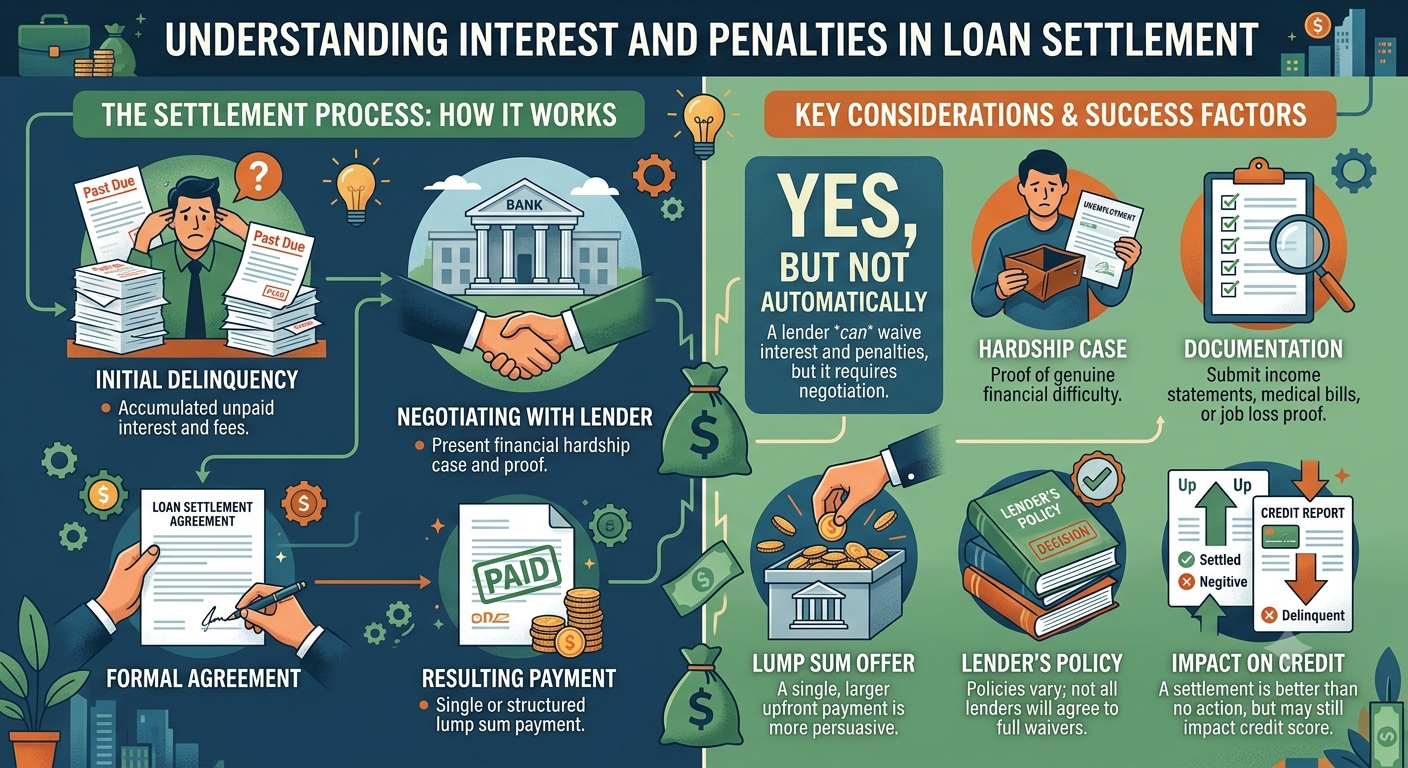
When borrowers fall behind on monthly loan EMIs or credit card payments, compounding interest, penal charges, late fees, and bounce charges quickly stack up. Over a few months of default, these added penalty fees can inflate the overall balance well beyond the original loan principal, making repayment seem mathematically impossible.
When facing severe financial distress, borrowers often ask: Can interest and penalties actually be waived during a loan settlement?
The answer is a definitive yes. In fact, complete waivers of accumulated penal interest, late fees, and bounce charges form the mandatory starting point of almost every One-Time Settlement (OTS) negotiated with banks and Non-Banking Financial Companies (NBFCs).
Understanding the Anatomic Structure of Defaulted Debt
To understand how interest and penalties get waived, it helps to break down the total claim amount demanded by lenders into three distinct categories:
+-------------------------------------------------------------------------------+
|                    STRUCTURE OF A DEFAULTED LOAN CLAIM                        |
+-------------------------------------------------------------------------------+
| 1. Core Principal Balance  | The actual borrowed capital remaining unpaid.     |
| 2. Base Contracting Interest| Normal agreement interest accrued up to default.|
| 3. Penalties & Penal Interest| Compounded late fees, bounce charges, penal %|
+-------------------------------------------------------------------------------+
When an account defaults past 90 days and is classified as a Non-Performing Asset (NPA), lenders recognize that penal charges are artificial accounting inflations. During settlement discussions, credit committees are routinely authorized to eliminate these extra fees to facilitate a realistic lump-sum recovery.
What Penal Fees Are Eligible for 100% Waiver?
During a structured settlement, lenders routinely grant full waivers on the following charges:
- Penal Interest Rates: Extra interest percentages (often 2% to 3% per month) levied on overdue balances.
- Cheque / Auto-Debit Bounce Charges: Accumulated fees charged for failed electronic clearing (NACH) or bounced cheques.
- Late Payment Penalties: Fixed recurring administrative fines applied for missing monthly payment deadlines.
- Compounding Interest Overhead: Multiplied interest calculated on top of accumulated unpaid penalties.
In addition to waiving 100% of these penalty fees, lenders frequently offer a discount on the core principal balance (ranging from 20% to 60%) depending on the severity of the borrower’s hardship.
How to Convince Banks to Waive Penal Fees
Banks do not offer penalty waivers automatically; borrowers must proactively request them through a structured negotiation process:
Step 1: Demand an Itemized Statement of Account
Request a detailed breakdown from the lender showing the exact distinction between the base principal, normal interest, and penalty charges.
Step 2: Establish Involuntary Hardship
Lenders require objective proof that default occurred due to involuntary circumstances—such as job loss, medical emergencies, or severe business downturns—rather than willful non-payment.
Step 3: Present a Written Hardship Proposal
Submit a formal letter to the bank’s Nodal Officer or Recovery Manager. Request an explicit 100% waiver of all penal interest, bounce charges, and late fees, and propose a realistic lump-sum payment toward the compromised principal balance.
Step 4: Verify Terms in an Official Sanction Letter
Never make a settlement payment based on verbal promises. Ensure the official Settlement Sanction Letter explicitly states that all penal charges are waived and that the paid sum constitutes full and final satisfaction of the account.
Penalty Waiver Comparison: Standard Payment vs. Settlement
| Parameter | Standard Repayment | One-Time Settlement (OTS) |
|---|---|---|
| Penal Interest & Bounce Fees | 100% Payable | 0% (100% Waived) |
| Accumulated Late Charges | 100% Payable | 0% (100% Waived) |
| Principal Amount | 100% Payable | Discounted (30%–60% Savings) |
| Account Status Outcome | Marked “Closed” | Marked “Settled” |
Helpful Resources and Guidance
Navigating bank credit committees, auditing inflated balance statements, and negotiating maximum penalty waivers requires specialized expertise. Explore these dedicated resources for legal and administrative support:
- Consult a certified loan settlement expert to evaluate your eligibility for 100% penalty waivers.
- Explore comprehensive negotiation plans for credit cards and personal loans through loan settlement services.
- Learn how to calculate realistic settlement waivers using complete loan settlement resources.
- Shield yourself from recovery harassment and unfair penal charges with a trusted loan settlement agency.
- Review your itemized account statements and bank letters with an accredited loan settlement expert.
- Waive illegal bounce charges and negotiate optimal principal discounts through specialized loan settlement services.
- Manage bank legal notices and recovery communications supported by an established loan settlement agency.
- Understand Reserve Bank of India (RBI) compromise frameworks with professional loan settlement advice.
- Safeguard your personal assets and secure written waiver guarantees from a skilled loan settlement expert.
- Obtain institutional representation and direct bank escalation via dedicated loan settlement services.
- Achieve full legal discharge and obtain your official No Dues Certificate (NDC) with an experienced loan settlement agency.
Final Thoughts
Compounding penal charges and late fees can make defaulted debt feel insurmountable, but they should never prevent you from resolving your obligations. By presenting verified hardship documentation, negotiating through formal channels, and obtaining an official sanction letter, borrowers can successfully eliminate all penal charges and settle their loans safely.