
Completing a One-Time Settlement (OTS) on an outstanding loan or credit card account brings immense relief to borrowers facing financial distress. It stops the compounding of penal interest, halts recovery calls, and protects you from impending legal action. However, the settlement process is not officially finished the moment your final payment clears the bank.
In the financial and legal world, documentation is everything. Without proper paperwork confirming that your debt has been compromised and satisfied according to agreed terms, you remain vulnerable to future recovery demands, balance miscalculations, and incorrect reporting to credit bureaus. Maintaining an organized physical and digital dossier of post-settlement papers is essential to safeguard your financial recovery.
Key Post-Settlement Documents Every Borrower Must Retain
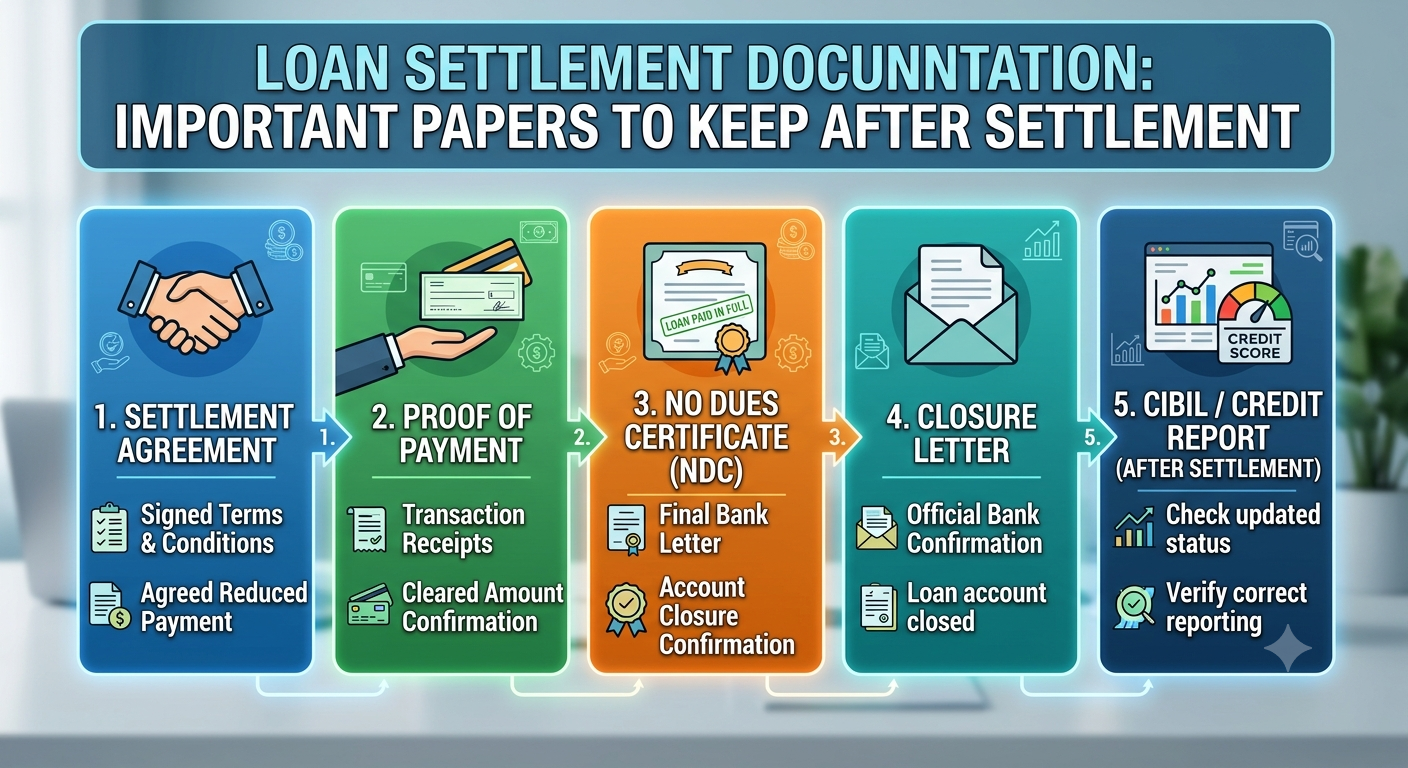
To ensure complete legal discharge and protect yourself against future claims, secure and preserve these essential records permanently:
+-------------------------------------------------------------------------------+
|                  CRITICAL LOAN SETTLEMENT DOCUMENTATION                       |
+-------------------------------------------------------------------------------+
| 1. Settlement Sanction Letter (Printed on Bank Letterhead)                    |
| 2. Payment Receipts & Bank Account Statements (Proof of Remittance)           |
| 3. No Dues Certificate (NDC) / No Objection Certificate (NOC)                 |
| 4. Legal Case Withdrawal & Section 138 Termination Notices                    |
| 5. Updated Credit Bureau Reports (CIBIL / Experian Status Verification)       |
+-------------------------------------------------------------------------------+
1. Official Settlement Sanction Letter
The Sanction Letter is the foundational contract of your settlement. Issued directly by your lender’s authorized signatory or credit committee, this letter outlines the exact terms under which the bank agrees to compromise the debt.
Ensure this document explicitly contains:
- The original loan account number and total outstanding balance.
- The negotiated lump-sum compromised settlement amount.
- The exact payment due date (or schedule of short-term installments).
- A clear clause confirming that paying this amount constitutes full and final satisfaction of the account.
2. Payment Proofs and Transaction Receipts
Never rely solely on digital bank notifications. Retain hard copies and digital receipts for every transaction made toward the settlement amount.
- Cheque/Demand Draft Acknowledgments: Deposit slips bearing official bank stamps.
- Online Transfer Receipts: Transaction IDs showing complete account numbers and transfer dates.
- Bank Statements: Highlighted bank statements proving funds successfully left your account and cleared on time.
3. No Dues Certificate (NDC) or No Objection Certificate (NOC)
The No Dues Certificate is the single most important document you will receive after completing payment. Issued by the bank within 15 to 45 days of final settlement, this certificate formally confirms that you no longer owe any money to the institution. Without an official NDC, a lender or third-party recovery agency could later argue that the remaining balance was merely deferred, not waived.
4. Court Case Withdrawal & Legal Discharge Letters
If your loan default had progressed to legal proceedings—such as notices under Section 138 of the Negotiable Instruments Act (cheque bounce) or Debt Recovery Tribunal (DRT) filings—you must secure formal confirmation that these actions have been terminated. Request certified copies of the bank’s court applications withdrawing pending lawsuits or police complaints.
5. Updated Credit Reports
Approximately 30 to 60 days following settlement, download fresh credit reports from major bureaus like CIBIL, Experian, and CRIF High Mark. Verify that the account status reflects “Settled” or “Closed” with a zero balance owing. Store these reports alongside your NDC to dispute any future credit reporting errors.
Document Retention Guidelines and Action Steps
| Document Type | Source | Purpose | Retention Period |
| Sanction Letter | Bank Credit Committee | Proves agreed settlement sum | Permanently |
| Payment Receipts | Depositing Bank | Proves timely payment execution | Permanently |
| No Dues Certificate | Bank Nodal Officer | Formal discharge of liability | Permanently |
| Legal Withdrawal | Jurisdictional Court | Prevents future legal claims | Permanently |
| Credit Report | Credit Bureaus (CIBIL) | Verifies zero balance reporting | 7 Years |
Essential Resources for Post-Settlement Verification
Managing bank communications, securing missing discharge letters, and correcting credit bureau records requires technical knowledge and advocacy. Explore these dedicated resources for assistance:
- Gain clarity on post-settlement legal documentation by consulting a certified loan settlement expert.
- Explore end-to-end legal discharge assistance and debt resolution through loan settlement services.
- Learn how to audit post-settlement paperwork using complete loan settlement guides.
- Prevent future recovery disputes and legal hassles by partnering with a trusted loan settlement agency.
- Review your Sanction Letter and No Dues Certificate with a qualified loan settlement expert.
- Ensure full waiver of penal interest and balance clearance with specialized loan settlement services.
- Resolve pending court notices and legal withdrawals supported by an established loan settlement agency.
- Understand credit bureau dispute protocols and status updates through expert loan settlement advice.
- Protect your financial freedom and personal assets with guidance from a skilled loan settlement expert.
- Obtain administrative support for securing pending bank certificates via professional loan settlement services.
- Verify full legal closure and obtain your official NDC with help from a reputable loan settlement agency.
Final Thoughts
A loan settlement is only as secure as the paperwork backing it up. By maintaining an organized file containing your Sanction Letter, payment proofs, No Dues Certificate, legal withdrawal papers, and updated credit reports, you create an unassailable shield against future claims and lay a strong foundation for your long-term financial recovery.